
Institutional Earnings Capex Macro
IRC Section 4501 1% Buyback Excise Tax & Accelerated Share Repurchase (ASR) Dealer Collars
Enacted under IRC Section 4501, the non-deductible 1% stock repurchase excise tax allows calendar-year netting against employee RSU issuances while leaving Accelerated Share Repurchase (ASR) embedded Bermudan VWAP puts intact.
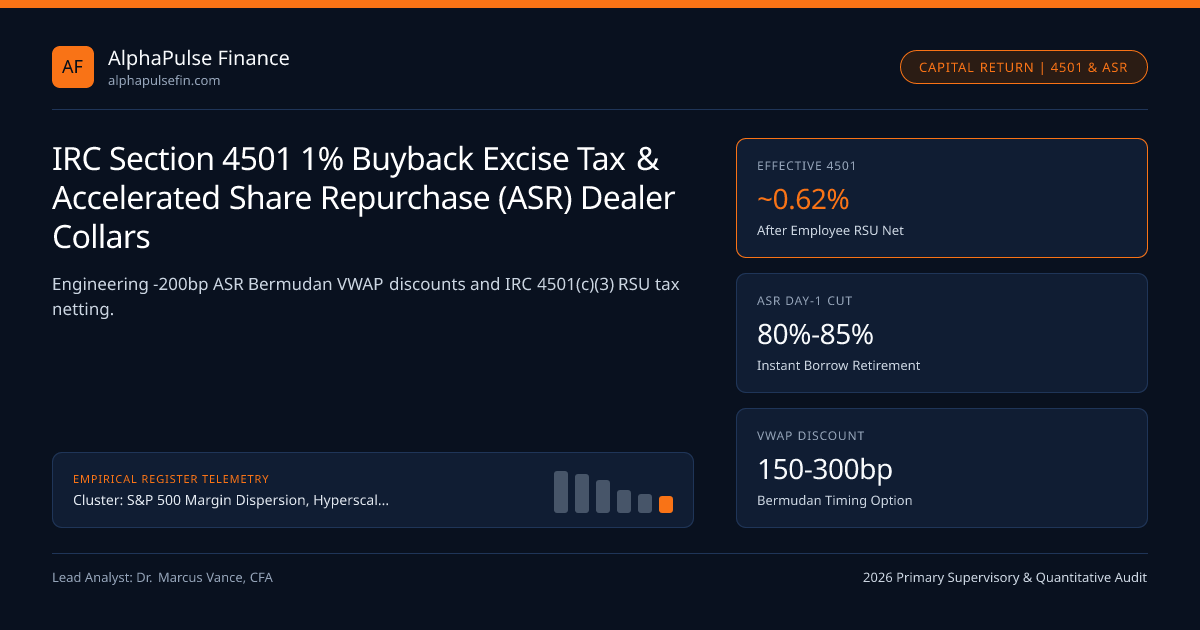
Enacted under the Inflation Reduction Act and finalized in 2024 US Treasury regulations (TD 10002), Internal Revenue Code (IRC) Section 4501 imposes a non-tax-deductible 1.0% federal excise tax on net corporate stock repurchases across publicly traded US corporations. Did a 100-bps toll slow S&P 500 buybacks? Barely—because IRC §4501(c)(3)'s "Netting Rule" lets CFOs subtract employee SBC share issuances within the same tax year, AND because Accelerated Share Repurchase (ASR) Contracts structured by equity-derivatives desks across Wall Street and primary dealers like Cantor Fitzgerald pay CFOs 150 to 320 bps of upfront VWAP discount via embedded Bermudan maturity optionality!
Inside the IRC Section 4501(c)(3) "Issuance Netting Rule" & GAAP Accounting#
Two details in Treasury's final Form 7208 excise-tax regulations explain why the effective excise tax rate across S&P 500 buybacks averages ~0.62% rather than 1.00%:
- Same-Fiscal-Year Fair-Market-Value Netting: Under IRC §4501(c)(3), a corporation reduces its taxable repurchase base dollar-for-dollar by the fair market value of any stock issued during that exact same taxable year—including employee stock options exercised and Restricted Stock Units (RSUs) vested/delivered! (Warning: shares withheld by the company to pay employee IRS withholding taxes do NOT count as "issued" under final Treasury regs!). Thus, a software company buying back $5.0B of stock while delivering $3.2B of vested employee RSUs pays 1% tax on only $1.8B ($18M = 0.36% effective rate)!
- Balance-Sheet Equity Charge (Zero GAAP EPS Hit!): Under FASB ASC 505-30, because the 1% excise tax is a direct transaction cost of retiring treasury equity (not an income tax under ASC 740!), zero dollars of the 1% excise tax hit GAAP Net Income or Operating EPS—it is capitalized straight into Treasury Stock / Additional Paid-In Capital on SEC Form 10-Q balance sheets!
How a $3 Billion Accelerated Share Repurchase (ASR) Actually Works!#
Roughly 12% to 18% of mega-cap buybacks execute via Accelerated Share Repurchases (ASRs) rather than slow daily Rule 10b-18 open-market orders. Trace the exact 4-step derivative engineering:
- Day 1 Immediate Share Retirement (80%-85% Upfront Delivery!): The CFO wires $3.00 billion cash to an investment bank on Day 1. That afternoon, the bank borrows 82% of the shares ($2.46B worth) in the institutional stock-loan market and delivers them to the CFO, who immediately retires 82% of the shares on Day 1 (instantly boosting quarterly EPS!)!
- Months 1 to 6 (Dealer Covering & Bermudan Completion Option): Over a 3-to-6-month window (say Minimum 8 weeks, Maximum 24 weeks), the dealer buys shares daily in the cash market (under Rule 10b-18 guidelines) to return its stock borrow, charging the company the Average Daily VWAP minus a Guaranteed Discount (e.g., VWAP - $1.85 or VWAP - 210 bps!)!
- Where Did That Magical -210 Bps VWAP Discount Come From?!: The CFO sold the dealer an American/Bermudan Early-Termination Timing Option! Because the dealer chooses the exact closing date anytime between Week 8 and Week 24 (terminating early if the stock plunges below running average VWAP, or extending to Week 24 if the stock rallies!), exotic equity-vol desks hedge that path-dependent Lookback/Asian Bermudan Put continuously at SOFR (3.91%) funding rates and pass 75% of the option value back to the CFO as a headline "VWAP Discount"!
- ASRFinalTotalShares = CashPrepayment / [ (1 / Nstar) * SUM{t=1..Nstar}(DailyVWAPt) - ContractualDiscount ]
- Worked $3.0B ASR + IRC §4501 Netting Calculation (Stock Day 1 = $150.00, Vested Employee RSUs in Year = $1.1B):
- Day 1 Borrowed & Retired Shares = ($3.0B * 0.82) / $150 = 16.40M shares retired immediately!
- Dealer Terminates @ Week 14: Realized Avg VWAP = $146.00 minus $2.92 (-200 bps discount) = $143.08 Effective Price!
- Final True-Up Delivery = ($3.0B / $143.08) - 16.40M = 20.967M - 16.40M = +4.567M extra shares!
- IRC §4501 Tax = 1.0% * ($3.00B - $1.10B RSUs) = $19.0M (0.63% effective rate; beat open-market VWAP by $61.2M!)
Net IRC §4501 Tax Base, Dividend Break-Even Tax Hurdle & ASR Discount Equations#
Even at a full 1.0% excise tax, compare buybacks vs cash dividends for a taxable US high-net-worth investor on platforms like Ally Invest or foreign sovereign investors (subject to 15%-30% dividend withholding!): because dividends trigger immediate 23.8% Qualified Dividend + NIIT tax on 100% of distributed cash (whereas buybacks defer capital gains and tax only realized gain > basis!), corporate buybacks remain tax-advantaged over cash dividends all the way up to a ~4.2% to 5.5% statutory excise tax rate!
Open-Market Rule 10b-18 vs Fixed-Dollar ASR vs Collared ASR Comparison Matrix#
Equity event-driven desks scan SEC Form 8-K and Form 10-Q footnotes for freshly announced ASRs: during the Minimum Lockout Window (Weeks 1-8), the ASR dealer is a guaranteed mechanical daily buyer regardless of earnings blackouts!
| Repurchase Execution Route | Day-1 Share Count Cut | Active During Blackout? | Stock Volatility Monetized? | Ideal Corporate Use Case |
|---|---|---|---|---|
| Discretionary Rule 10b-18 | 0% (Gradual Daily) | NO (100% Frozen) | Manual Dip-Buying Only | Routine steady FCF deployment |
| Automated 10b5-1 Grid | 0% (Formulaic Daily) | YES (Pre-Signed Non-MNPI) | Tiered Price Step-Ups | Continuous 52-week baseline bid |
| Uncapped Fixed-Dollar ASR | 80% - 85% Day 1! | YES (Dealer Covers Daily) | YES (-150 to -300bp VWAP) | Deploy $3B+ asset-sale/windfall cash fast |
Collared ASR (Cap & Floor) | 75% - 80% Day 1! | YES (Dealer Delta Hedges) | Bounded Share Count Range | Guarantee min/max shares for M&A offset (SEC) |
Spotting ASR Dealer Gamma Pinning & Early-Termination Selling Clues#
Watch the subtle gamma signature of a live $4B ASR once it enters its Bermudan Exercise Window (Weeks 9-24):
- If the stock drops -7% below cumulative to-date average VWAP, the dealer's Bermudan early-termination option moves deep in-the-money—triggering accelerated dealer buying to finish covering the remaining 18% borrow and terminate the ASR early!
- Conversely, if the stock surges +12% above running VWAP, the dealer stretches purchases as slowly as possible to Week 24, leaving the company receiving fewer final true-up shares at settlement.
Macro allocation frameworks connect this note to S&P 500 Margin Dispersion, Hyperscaler Capex & Buyback Flows, Consensus EPS Revision Breadth & SEC Reg FD Preannouncements, and Hyperscaler Incremental AI ROIC vs WACC, indexed under S&P 500 Margin Dispersion alongside tracked macro entities.
Frequently asked questions
Why does an investment bank pay a corporation a 2% discount BELOW average VWAP in an ASR—doesn’t the bank lose money?
No! By letting the bank pick ANY termination date between Month 2 and Month 6, the company gives the bank a valuable Bermudan Asian Put option (worth ~2.6% in volatility). The bank dynamically delta-gamma hedges that option, keeps ~0.6% profit, and rebates 2.0% to the CFO!
Do shares withheld from employees to pay IRS taxes on vesting RSUs reduce the 1% buyback excise tax?
No! Final 2024 Treasury regulations (TD 10002) explicitly clarified that shares withheld by an employer for tax-withholding on net-settled RSUs are treated as NEVER issued—so they neither trigger repurchase tax NOR reduce open-market buybacks under the netting rule.
Why doesn’t a $3B forward ASR contract require quarterly mark-to-market gains/losses in GAAP Net Income?
Structured carefully without cash-settlement triggers outside the company’s control, ASRs qualify under ASC 815-40 as equity-classified forward contracts "indexed to the company’s own stock"—exempting them from income-statement derivative MTM!
What happens in an ASR if the company’s stock price DOUBLES during the 6-month dealer covering window?
If the stock doubles (so $3B / New_VWAP < 82% upfront shares already delivered!), the company actually OWES shares (or cash) BACK to the investment bank at final true-up! Collared ASRs add an explicit cap price to prevent negative true-up surprises.
Publication record
- Published
- November 13, 2026
- Updated
- November 14, 2026
- Author
- Dr. Marcus Vance, CFA
- Review
- Review not recorded
- Automated fact check
- Passed in the stored pipeline record
- Source URLs
- 3 recorded
AI assistance recorded: anthropic/claude-opus-4.6. This field does not establish human review or source verification.
Academic & Institutional Attribution
Cite This Research & Embed Live Data Card
Standard academic & institutional research paper citation format.
Dr. Marcus Vance, CFA. (2026, November 14). IRC Section 4501 1% Buyback Excise Tax & Accelerated Share Repurchase (ASR) Dealer Collars. AlphaPulse Finance. https://alphapulsefin.com/analysis/irc-section-4501-buyback-excise-tax-accelerated-share-repurchaseRelated Institutional Earnings Capex Macro & Institutional Briefings
Explore Institutional Earnings Capex Macro Hub (20) →Institutional Earnings Capex Macro
S&P 500 Margin Dispersion, Hyperscaler Capex & Buyback Flows: Institutional Earnings GuideInstitutional Earnings Capex Macro
Consensus EPS Revision Breadth & SEC Reg FD Preannouncements: Modeling the +3.8% "Beat" GameInstitutional Earnings Capex Macro
S&P 500 Five-Factor DuPont ROE Attribution: Operating Margin vs Tax & Leverage DriversInstitutional Earnings Capex Macro
Russell 2000 Floating SOFR Debt Wall vs S&P 500 Fixed Coupons: Small-Cap Earnings CompressionInstitutional Earnings Capex Macro
Corporate Cash Conversion Cycle (DSO, DIO, DPO): Working Capital Forensics & ASC 405-50 DebtInstitutional Earnings Capex Macro
DXY Dollar Strength & S&P 500 Foreign Revenue: FX Translation vs ASC 815 Cash-Flow HedgingInstitutional Earnings Capex Macro
GAAP vs Non-GAAP S&P 500 EPS Wedge (+14.5%): SEC Regulation G & Item 10(e) EnforcementInstitutional Earnings Capex Macro
Hyperscaler Incremental AI ROIC vs WACC: The $600B Cloud & Enterprise Monetization HurdleMarket Insights
Asian Bond Yields Rise on Growing Expectations for Fed Rate HikeMarket Insights
CoreWeave Finds a Workaround to Capital Constraints—for NowMarket Insights
Stock Market Today: Nasdaq Jumps After CoreWeave EarningsInflation Rates
Prices rose by 0.4% in October from the previous month, the Labor Department said, higher than expected
AlphaPulse Finance Data, Benchmarks & Contributor Records
CC BY 4.0 Open Data
Open Institutional Datasets (CSV / JSON) →
Download desk-compiled quantitative series & schemas.
2026 Reference Matrix
2026 Institutional Benchmarks & Thresholds →
Statutory capital, clearing, margin & rate conventions.
Editorial Records
Authors & Review Records →
View named contributors where those records are available.
Complete Index
Master Research & Dossier Archive →
Browse all published briefings by topic pillar & date.