
Institutional Earnings Capex Macro
Hyperscaler Data-Center Power Bottlenecks: Grid Interconnection Queues, Nuclear PPAs & HPC Landlords
With US regional transmission interconnection queues stretching 4 to 7 years and AI rack densities jumping from 12 kW to 130+ kW, hyperscalers pay massive premiums for energized megawatts from nuclear IPPs and HPC developers.
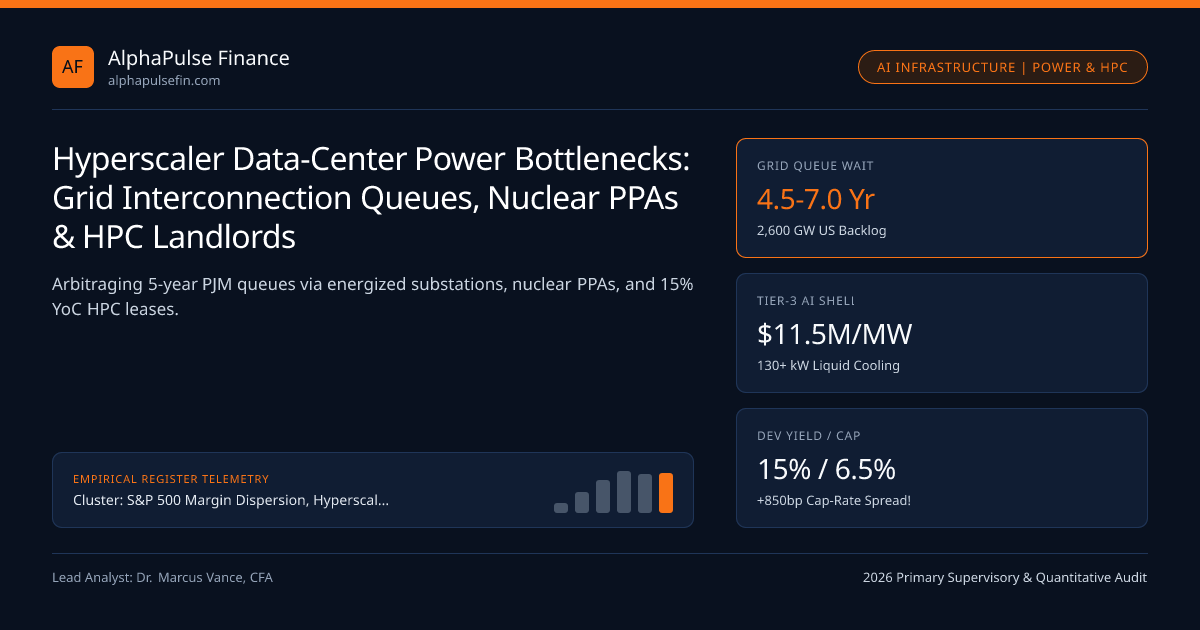
Silicon is no longer the primary bottleneck in US artificial intelligence infrastructure—energized high-voltage grid megawatts (MW) and large power transformers now govern deployment timelines! Across PJM Interconnection (Northern Virginia "Data Center Alley"), ERCOT, and WECC, utility transmission interconnection queues exceed 2,600 gigawatts (4.5 to 7.0 years median wait time) while single-rack thermal densities leap 10x from 12 kW (CPU cloud) to 120-140 kW (Blackwell/Rubin liquid-cooled GPU racks)! Desperate for 2026-2028 "Time-to-Power," investment-grade hyperscalers are signing 20-year Nuclear Power Purchase Agreements (PPAs) and 15-year triple-net leases with energized HPC developers and Bitcoin-to-AI power-conversion landlords including Applied Digital Corporation and Bitfarms!
Why PJM Capacity Auctions Exploded 9x & FERC Scrutinized "Behind-the-Meter" Nuclear!#
Two regulatory shocks at the Federal Energy Regulatory Commission (FERC) and regional grid operators (PJM / ERCOT) transformed US power economics in 2025-2026:
- PJM Base Residual Auction (BRA) Capacity Price Explosion: Driven by coal/gas plant retirements colliding with 24/7 gigawatt data-center load forecasts, PJM clearing prices for reliable generation capacity surged nearly 900% (from $28.92/MW-day to $269.92+/MW-day and hitting statutory FERC caps!), lifting wholesale merchant nuclear and natural-gas independent power producer (IPP) cash flows!
- FERC Co-Located Load Ruling (Talen Susquehanna / Amazon Precedent): When hyperscalers sought to plug data centers directly "Behind-the-Meter" into existing nuclear reactors (paying $105-$115/MWh—more than 2x wholesale power—for 99.9% carbon-free baseload!), FERC intervened to ensure co-located AI campuses still pay fair transmission grid-reliability charges rather than shifting grid costs onto residential ratepayers (forcing "Front-of-the-Meter" network-upgrade PPAs and dedicated gas-turbine bridge microgrids!).
The "Bitcoin-to-HPC Conversion" Arbitrage: Valuing Energized Substations Per MW#
Why did cloud hyperscalers and project-finance desks at Wall Street banks and primary dealers like Cantor Fitzgerald start signing multi-billion-dollar 15-Year Triple-Net (NNN) HPC Colocation Leases with specialized infrastructure operators like Applied Digital Corporation (Ellendale North Dakota 400MW+ campus) and evaluating high-voltage substation portfolios across miners like Bitfarms?
Examine the Replacement-Time & Per-Megawatt Cap-Rate Arbitrage:
- Building a brand-new Tier-III Direct-to-Chip Liquid-Cooled AI Data Center (excluding the GPUs inside!) costs $10.5 million to $13.5 million per Critical IT Megawatt (vs $1.2M/MW for air-cooled crypto sheds)—and ordering a 345-kV high-voltage step-down transformer alone carries a 110-to-160-week supply-chain lead time!
- Operators who already possess approved FERC/utility interconnect permits and energized 200-500 MW substations right now convert raw megawatts into 14% to 17% Unlevered Yield-on-Cost ($1.55M-$1.85M annual NOI per MW on $11M/MW build cost), then finance 80%-85% of construction via investment-grade SASB / ABS Project Debt at SOFR + 175-225 bps backed by AA/AAA hyperscaler lease guarantees disclosed in SEC Form 8-K filings!
- DeveloperEquityCreationperMW = (AnnualTripleNetNOIperMW / ExitInstitutionalCapRate) - CapexperMW
- Worked 400-MW Critical IT Liquid-Cooled AI Campus Economics (15-Year AA Hyperscaler NNN Lease):
- Build Cost = 400 MW * $11.50M/MW = $4.60 Billion | Contracted Year-1 NNN NOI = 400 MW * $1.725M/MW = $690.0M/yr (15.0% YoC!)
- Project-Finance Debt (82% of Cost = $3.77B @ 5.95%): Equity Check = $830M
- Stabilized Valuation @ 6.50% Cap Rate = $690.0M / 0.065 = $10.615 Billion -> $6.015B Net Value Creation (7.2x Equity MOIC!)
HPC Development Yield-on-Cost vs Capitalized Cap-Rate Value Creation Equations#
Valuing a stabilized 15-year AAA-credit-leased AI data center at a 6.25% to 6.75% Institutional Cap Rate (anchored to 4.32% 10Y Treasuries and 1.98% TIPS) generates >2.1x development value-to-cost the day the campus energizes!
AI Power Procurement Paths & Per-Megawatt Unit Economics Matrix (Q4 2026)#
Notice how Natural Gas CCGT + Onsite Aeroderivative Turbines emerged alongside Nuclear Restart PPAs (Three Mile Island / Palisades / Duane Arnold) as the dominant 2026-2029 bridge before Small Modular Reactors (SMRs) arrive post-2031!
| Power / Compute Strategy | Energization Timeline | All-In Power Cost ($/MWh) | FERC / Regulatory Hurdle | Representative Market Players |
|---|---|---|---|---|
Standard Utility Queue (Front) | 2030 - 2032 (5-7 Yrs) | $55 - $78 / MWh | Multi-state transmission upgrade cost | Regulated Utilities (PJM / ERCOT) |
| Energized Brownfield / HPC Pivot | 2026 - 2027 (Immediate!) | $52 - $68 / MWh | Already Permitted (High Scarcity!) | Applied Digital / Bitfarms |
| Nuclear Restart / Front-Meter PPA | 2027 - 2028 (2-3 Yrs) | $105 - $118 / MWh | FERC Co-Location Grid Cost Sharing | Constellation / Talen / Vistra |
| Behind-Meter NatGas Turbine Bridge | 18 - 24 Months | $75 - $95 / MWh | EPA Air Permits + Turbine Slot Queue | GE Vernova / Texas Permian Sites |
Underwriting HPC Landlord Credit: Lease Escalators, Make-Whole & Stranded-Asset Risk#
Equity and ABS credit committees stress-test third-party HPC data-center developers across three decisive contract clauses: (1) Parent vs Subsidiary Lease Guarantee (insist on top-tier AA/A Hyperscaler Parent guarantee, NEVER an uncapitalized SPV!), (2) 2.5% to 3.0% Annual Fixed Rent Escalators (hedging inflation!), and (3) Liquid-Cooling PUE <= 1.22 (ensuring the facility can host 2030+ 250-kW/rack chips after GPU cycles turn over).
Related empirical studies—IRC Section 4501 1% Buyback Excise plus GAAP vs Non-GAAP S&P 500 EPS Wedge (+14.5%)—feed directly into S&P 500 Margin Dispersion, Hyperscaler Capex & Buyback Flows, the S&P 500 Margin Dispersion hub, and regulatory bodies.
Frequently asked questions
Why can’t a Bitcoin mining shed simply unplug ASIC miners and plug in Nvidia Blackwell AI GPUs tomorrow?
Only the high-voltage substation and grid interconnect transfer directly! Bitcoin sheds use cheap Curtailable 90%-uptime air-cooled warehouses ($1.1M/MW), whereas AI training requires 99.995% Tier-III uptime, UPS/diesel backup, fiber redundancy, and $11.5M/MW closed-loop liquid cooling!
Why did FERC block Talen Energy and Amazon’s original expanded "Behind-the-Meter" Susquehanna nuclear amendment?
Regulated utilities (AEP/Exelon) argued that carving 960 MW of existing baseload nuclear power straight off the PJM grid without paying transmission charges tightened grid reserve margins and hiked power bills for everyday families!
What is "Critical IT Megawatts" versus "Gross Utility Megawatts" in data-center lease math?
At a Power Usage Effectiveness (PUE) of 1.25, delivering 400 MW of Critical IT Power to server racks requires 500 MW of Gross Utility Grid Power (with 100 MW consumed by chillers, pumps, and transformer step-down losses)—rents always quote per Critical IT MW!
How do HPC developers finance $4.6B campuses when their own equity market cap is only $2B-$4B?
Once an AA/AAA hyperscaler signs a binding 15-year Hell-or-High-Water Triple-Net Lease, project-finance lenders underwrite the *tenant’s* AA credit—advancing 80%-85% construction-to-permanent ABS/SASB debt non-recourse to the parent!
Publication record
- Published
- November 13, 2026
- Updated
- November 14, 2026
- Author
- Dr. Marcus Vance, CFA
- Review
- Review not recorded
- Automated fact check
- Passed in the stored pipeline record
- Source URLs
- 3 recorded
AI assistance recorded: anthropic/claude-opus-4.6. This field does not establish human review or source verification.
Academic & Institutional Attribution
Cite This Research & Embed Live Data Card
Standard academic & institutional research paper citation format.
Dr. Marcus Vance, CFA. (2026, November 14). Hyperscaler Data-Center Power Bottlenecks: Grid Interconnection Queues, Nuclear PPAs & HPC Landlords. AlphaPulse Finance. https://alphapulsefin.com/analysis/hyperscaler-datacenter-power-interconnection-nuclear-ppa-capexRelated Institutional Earnings Capex Macro & Institutional Briefings
Explore Institutional Earnings Capex Macro Hub (20) →Institutional Earnings Capex Macro
S&P 500 Margin Dispersion, Hyperscaler Capex & Buyback Flows: Institutional Earnings GuideInstitutional Earnings Capex Macro
IRC Section 4501 1% Buyback Excise Tax & Accelerated Share Repurchase (ASR) Dealer CollarsInstitutional Earnings Capex Macro
Consensus EPS Revision Breadth & SEC Reg FD Preannouncements: Modeling the +3.8% "Beat" GameInstitutional Earnings Capex Macro
S&P 500 Five-Factor DuPont ROE Attribution: Operating Margin vs Tax & Leverage DriversInstitutional Earnings Capex Macro
Russell 2000 Floating SOFR Debt Wall vs S&P 500 Fixed Coupons: Small-Cap Earnings CompressionInstitutional Earnings Capex Macro
Corporate Cash Conversion Cycle (DSO, DIO, DPO): Working Capital Forensics & ASC 405-50 DebtInstitutional Earnings Capex Macro
DXY Dollar Strength & S&P 500 Foreign Revenue: FX Translation vs ASC 815 Cash-Flow HedgingInstitutional Earnings Capex Macro
GAAP vs Non-GAAP S&P 500 EPS Wedge (+14.5%): SEC Regulation G & Item 10(e) EnforcementMarket Insights
U.S. Stocks Slip on Inflation, AI WorriesMarket Insights
Asian Bond Yields Rise on Growing Expectations for Fed Rate HikeMarket Insights
CoreWeave Finds a Workaround to Capital Constraints—for NowMarket Insights
Stock Market Today: Nasdaq Jumps After CoreWeave Earnings
AlphaPulse Finance Data, Benchmarks & Contributor Records
CC BY 4.0 Open Data
Open Institutional Datasets (CSV / JSON) →
Download desk-compiled quantitative series & schemas.
2026 Reference Matrix
2026 Institutional Benchmarks & Thresholds →
Statutory capital, clearing, margin & rate conventions.
Editorial Records
Authors & Review Records →
View named contributors where those records are available.
Complete Index
Master Research & Dossier Archive →
Browse all published briefings by topic pillar & date.