
Inflation Breakevens Real Rates
Real 2s10s TIPS Yield Curve Slope: Auditing Ex-Ante FOMC Monetary Restrictiveness
Purged of nominal tariff and oil breakeven distortions, the Seasonally Adjusted 2s10s Real TIPS Curve and Ex-Ante 1-Year Real Policy Rate minus r-star (+75 bps) measure true FOMC monetary restrictiveness across business cycles.
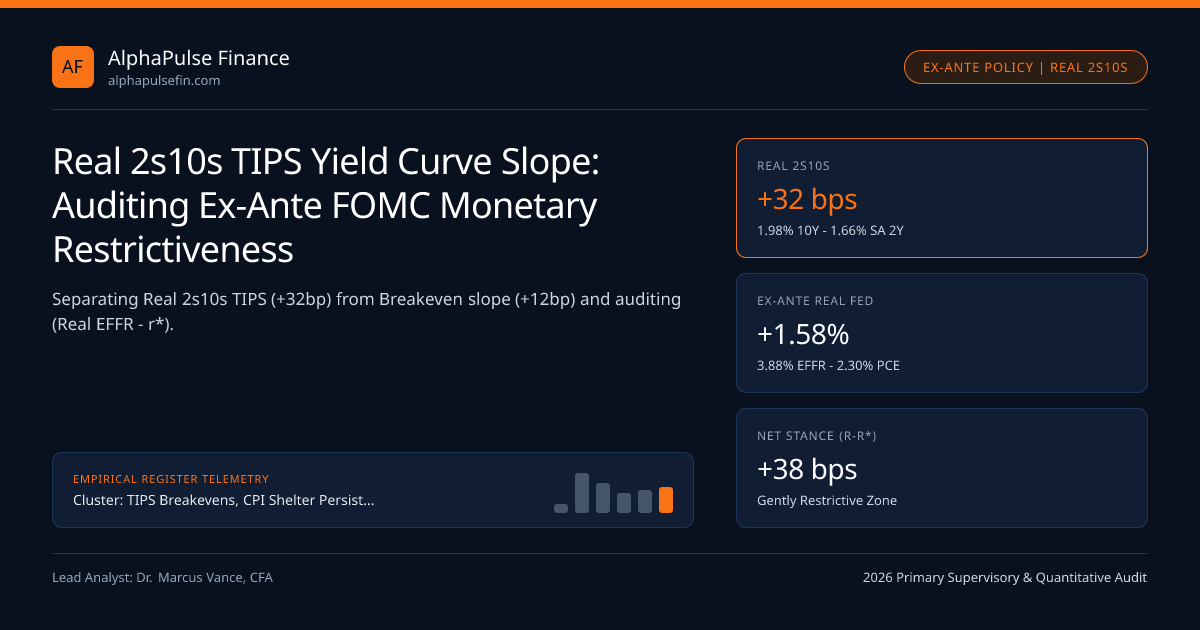
During 2022-2024, the Nominal 2s10s Treasury Yield Curve stayed inverted for a record 26 consecutive months without an immediate NBER recession—baffling commentators who forgot that 35 to 55 bps of that nominal inversion was merely high spot inflation declining back toward 2% (an inverted inflation breakeven curve!)! Stripping out inflation expectations to examine the Seasonally Adjusted Real 2s10s TIPS Curve (comparing 2Y SA Real TIPS against 10-Year TIPS Real Yields (1.98%)) alongside Ex-Ante Real EFFR minus r* inside the FOMC 3.75%-4.00% Corridor reveals the exact moment monetary policy transitions from actively restrictive to neutral!
Why Nominal 2s10s Confuses Disinflation With Recession!#
Write out the exact Fisher identity for the Nominal 2s10s Slope: Nominal_2s10s = (10Y_Real_TIPS - 2Y_SA_Real_TIPS) + (10Y_Breakeven - 2Y_SA_Breakeven) — expressed cleanly without backticks: Nominal 2s10s Slope equals Real 2s10s Slope PLUS Breakeven 2s10s Slope!
Look at why Nominal 2s10s cried wolf in 2023:
- Suppose 2-year inflation is temporarily elevated at 3.2% (and expected to glide softly down to 2.2% without a recession!). That benign "immaculate disinflation" makes the Breakeven 2s10s Curve invert by -100 bps—dragging the Nominal 2s10s Curve deeply negative even if real growth is booming!
- Conversely, the Seasonally Adjusted Real 2s10s Curve (monitored by the Federal Reserve Board via Gurkaynak-Sack-Wright fitted real zero yields) inverts ONLY when the FOMC holds short-term Real Policy Rates (EFFR minus 1Y Expected PCE) substantially above long-run neutral real r* (~1.15% to 1.35%) and markets price inevitable real policy cuts!
Calibrating Ex-Ante Real FOMC Restrictiveness in Q4 2026 (+45 to +75 Bps)#
How restrictive is an FOMC 3.75%-4.00% Corridor (3.88% median EFFR) right now in late 2026?
Never subtract trailing 12-month inflation (ex-post real rate) when businesses borrow for next year's capex; subtract 1-Year Forward Expected Core PCE / Market-Based PCE (~2.25% to 2.40%) (or 1Y RBOB-adjusted ZCIS):
- Ex-Ante 1-Year Real Policy Rate: 3.88% EFFR - 2.30% Forward PCE = +1.58% Real Policy Rate.
- *Neutral Real Rate Benchmark (r)*: Blending NY Fed Holston-Laubach-Williams (~1.18%), Richmond Fed Lubik-Matthes (~1.55%), and FOMC SEP Longer-Run Median (3.00% Nominal - 2.00% PCE = +1.00% Real) places institutional consensus r near +1.20%.
- *Net Monetary Restrictiveness (r_real - r): +1.58% - 1.20% = +38 bps modestly restrictive (down from +245 bps peak restrictiveness when EFFR was 5.33%!), while 2s10s Real TIPS (1.98% 10Y minus 1.66% SA 2Y = +32 bps positive slope)** confirms successful soft-landing re-steepening!
- ExAnteMonetaryStancebps = (EFFR - Expected1YForwardPCE) - r*Neutral_Consensus
- Worked Q4 2026 FOMC "Passive Tightening Prevention" Calculation:
- If FOMC held EFFR frozen at 5.33% while Forward PCE cooled from 3.33% down to 2.30%:
- Ex-Ante Real Policy Rate would have PASSIVELY SURGED from +2.00% up to +3.03% (+183 bps above 1.20% r*!)
- Cutting Corridor to 3.75%-4.00% (3.88% EFFR) lowered Ex-Ante Real Rate to +1.58% (+38 bps gently restrictive!)
Fisher Curve Slope Identity & Ex-Ante Real Policy Gap Equations#
Notice how Real 2s10s Bull-Steepening (2Y SA Real Yield dropping from 2.85% down to 1.66% while 10Y Real holds at 1.98%) acts as the green light for cyclical credit and capex expansion across venues tracked by FINRA and CFTC!
Historical US Real 2s10s Curve Regimes & FOMC Cycle Turning Points#
Critically, when computing 2-year cash TIPS yields on trading screens at Cantor Fitzgerald or Atomic Capital, always strip NSA CPI seasonality first (otherwise April vs July 2Y TIPS seasonal kinks add +/-40 bps of fake slope!)!
| Macro Shock Scenario | Real 2s10s TIPS Slope | Breakeven 2s10s Slope | Nominal 2s10s Result | Optimal Rates Trade Expression |
|---|---|---|---|---|
| Immaculate Disinflation | Flat / Slightly Inv. | Deeply Inverted (-55bp) | Optically Inverted (False Recession!) | Fade recession panic; buy credit carry |
| Dovish FOMC Soft Landing | Bull-Steepens (+35bp) | Steepens (+15bp) | Strongly Steepens (+50bp) | Long Nominal + Real 2s10s Steepener |
| Import Tariff Stagflation | Bull-Steepens (+25bp) | Inverts Hard (-30bp!) | Stuck Near Zero (Cancels Out!) | Real 2s10s Steepener + 2s10s BEI Flattener! |
| QRA Fiscal Deficit Panic | Bear-Steepens (+30bp) | Bear-Steepens (+15bp) | Bear-Steepens (+45bp) | Short 30Y Swap Spreads (CFTC) |
Trading "Pure Real Steepeners" vs "Pure Breakeven Steepeners"#
Decomposing a classic Nominal 2s10s Steepener into its two orthogonal halves lets macro pods double Sharpe ratios:
- If FOMC Cuts Aggressively Into Sticky Inflation (Dovish Pivot / Fiscal Dominance): Put on BOTH a Real 2s10s TIPS Steepener (2Y Real plunges, 10Y Real sticky on QRA deficits) AND a Breakeven 2s10s Steepener!
- If Import Tariffs Hit While FOMC Pauses (Stagflation Lite): Nominal 2s10s gets stuck in a tug-of-war (Breakeven 2s10s inverts -25 bps while Real 2s10s steepens +25 bps = 0 bps Nominal move!)—making Long 2Y Breakevens / Real 2s10s Steepener vastly superior to dull Nominal 2s10s!
Historical calibration series link 5y5y Forward Inflation Swaps vs TIPS Breakevens, Cleveland Fed Trimmed-Mean & Median CPI vs Dallas Fed Trimmed PCE, and TIPS Breakevens, CPI Shelter Persistence & Forward Real Rates directly to TIPS Breakevens and tracked macro entities.
Frequently asked questions
Why did the Nominal 2s10s curve inversion of July 2022 - August 2024 fail to trigger a 2023 recession?
Roughly half of the -108 bps peak nominal inversion came from an inverted inflation breakeven curve (spot 6% CPI expected to normalize peacefully to 2.2%), while corporate 30Y fixed debt and fiscal deficits buffered the real economy!
What did Fed Governor Christopher Waller mean by "recalibration cuts" to prevent passive real tightening?
From the Taylor Principle (r_real = i_nominal - pi_expected), if i_nominal stays fixed at 5.33% while pi_expected drops from 3.5% to 2.2%, r_real rises automatically by +130 bps without a single FOMC hike—requiring nominal cuts just to hold real stance steady!
Where does the Federal Reserve Board publish official smoothed 2-year and 10-year zero-coupon Real TIPS yields?
Federal Reserve Statistical Release / FEDS Data feds200805 ("The TIPS Yield Curve and Inflation Compensation", Gurkaynak-Sack-Wright) provides daily smoothed zero-coupon real yields from 2 years to 20/30 years free of seasonal coupon kinks!
How does Real 2s10s behave right BEFORE an actual hard-landing recession starts?
Historically (2001, late 2007, early 2020), Real 2s10s first inverts (-50 to -90 bps) during late-cycle FOMC tightening, and the actual recession begins right AFTER Real 2s10s violently bull-steepens back above +25 bps as 2Y real yields crash!
Publication record
- Published
- November 13, 2026
- Updated
- November 15, 2026
- Author
- Dr. Marcus Vance, CFA
- Review
- Review not recorded
- Automated fact check
- Passed in the stored pipeline record
- Source URLs
- 3 recorded
AI assistance recorded: anthropic/claude-opus-4.6. This field does not establish human review or source verification.
Academic & Institutional Attribution
Cite This Research & Embed Live Data Card
Standard academic & institutional research paper citation format.
Dr. Marcus Vance, CFA. (2026, November 15). Real 2s10s TIPS Yield Curve Slope: Auditing Ex-Ante FOMC Monetary Restrictiveness. AlphaPulse Finance. https://alphapulsefin.com/analysis/real-2s10s-tips-yield-curve-slope-ex-ante-monetary-restrictivenessRelated Inflation Breakevens Real Rates & Institutional Briefings
Explore Inflation Breakevens Real Rates Hub (20) →Inflation Breakevens Real Rates
TIPS Breakevens, CPI Shelter Persistence & Forward Real Rates: Institutional GuideInflation Breakevens Real Rates
5y5y Forward Inflation Swaps vs TIPS Breakevens: Stripping Out Oil & Liquidity NoiseInflation Breakevens Real Rates
BLS CPI Shelter Persistence: 6-Month OER Panel Rotation vs New-Tenant Repeat Rent LagsInflation Breakevens Real Rates
BEA Core PCE vs BLS Core CPI Wedge: Scope, Weight & Fisher Substitution DecompositionInflation Breakevens Real Rates
TIPS Par Deflation Floor Convexity: Pricing Embedded 0% Put Options Across Issue VintagesInflation Breakevens Real Rates
10-Year TIPS Real Yields & S&P 500 Forward P/E Compression: Equity Duration RegimesInflation Breakevens Real Rates
NSA CPI 3-Month Indexation Lag & Front-End TIPS Seasonal Carry/Roll MechanicsInflation Breakevens Real Rates
Cleveland Fed Trimmed-Mean & Median CPI vs Dallas Fed Trimmed PCE: Outlier-Filtered SignalsMarket Insights
Gold Dims Amid Rising Fed Rate-Hike ExpectationsMarket Insights
U.S. Stocks Gain After CoreWeave Update Eases Some AI ConcernsEarnings Reports
Brookfield Earnings Buoyed by Fund Raising, Wealth Solutions GrowthMonetary Policy
The Inflation Fight May Be About to Turn Painful
AlphaPulse Finance Data, Benchmarks & Contributor Records
CC BY 4.0 Open Data
Open Institutional Datasets (CSV / JSON) →
Download desk-compiled quantitative series & schemas.
2026 Reference Matrix
2026 Institutional Benchmarks & Thresholds →
Statutory capital, clearing, margin & rate conventions.
Editorial Records
Authors & Review Records →
View named contributors where those records are available.
Complete Index
Master Research & Dossier Archive →
Browse all published briefings by topic pillar & date.