Inflation Breakevens Real Rates
5y5y Forward Inflation Swaps vs TIPS Breakevens: Stripping Out Oil & Liquidity Noise
Federal Reserve policymakers prioritize the 5-year, 5-year forward inflation swap (259 bps) over spot 10-year TIPS breakevens because forward extraction strips out 0-to-5-year energy shocks and cash TIPS repo illiquidity.
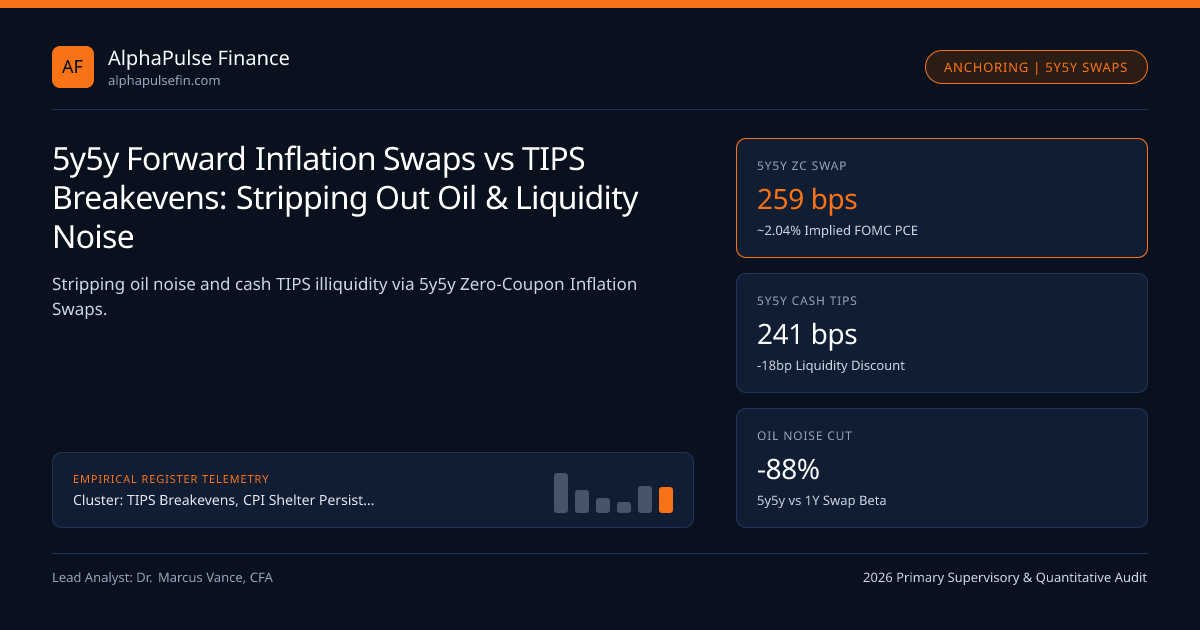
Whenever crude oil plunges -20% or import tariffs spike 1-year goods prices, spot 10-year TIPS breakevens benchmarked against 10-Year Real Yields (1.98%) and 10-Year Nominal Notes (4.32%) swing wildly—even though half of a 10-year bond's horizon lies inside the noisy first five years. To isolate whether long-horizon inflation expectations remain anchored to its 2.0% PCE mandate, the Federal Reserve tracks the 5-Year, 5-Year Forward (5y5y) Inflation Expectation Rate across both Zero-Coupon Inflation Swaps (259 bps) cleared under CFTC oversight and Forward Cash TIPS Breakevens (241 bps).
Zero-Coupon Inflation Swap (ZCIS) Cash-Flow Mechanics & Single-Bullet Compounding#
Unlike standard interest-rate swaps that exchange quarterly cash coupons, a standard USD Zero-Coupon Inflation Swap (ZCIS) cleared at LCH SwapClear has zero intermediate cash flows for its entire 5-year or 10-year life! Only a single compounded bullet net payment changes hands at final maturity T:
- Fixed-Rate Payer (Long Inflation): Pays Notional * [ (1 + K_Swap)^T - 1 ] at maturity.
- Floating CPI Payer (Short Inflation): Pays Notional * [ (RefCPIT / RefCPI0) - 1 ], using the exact same 3-month-lagged NSA CPI-U formula as US TIPS!
Because ZCIS requires zero cash bond repo financing (posting only ~2.8% to 4.2% LCH initial margin), UK/US pension funds hedging inflation-indexed liabilities and macro hedge funds strongly prefer paying fixed on 5Y and 10Y ZCIS over buying cash TIPS—structurally holding the ZCIS-minus-TIPS basis positive at +18 to +28 bps!
Why Cash 5y5y TIPS Forward Breakevens Require Modified-Duration Weighting#
Computing 5y5y in Zero-Coupon Swaps is exact exponential algebra ([(1 + S10)^10 / (1 + S5)^5]^(1/5) - 1). Computing 5y5y from coupon-bearing 5-Year and 10-Year Par Cash TIPS is trickier because coupon cash flows shorten modified duration below stated maturity!
If a 10-year TIPS has real modified duration of 8.95 years and a 5-year TIPS has real duration of 4.68 years, taking a naive 2 * BEI10Y - 1 * BEI5Y simple average leaves residual 0-to-5-year oil sensitivity! Desk strategists at dealers like Cantor Fitzgerald weight the forward leg by exact DV01 duration shares (w_5 = 4.68 / 8.95 = 52.3%) or extract 5y5y directly from the Federal Reserve's Gurkaynak-Sack-Wright (GSW) smoothed zero-coupon TIPS spline.
- ApproxDurationAdjustedCash5y5y = [ (Dur10 * BEI10) - (Dur5 * BEI5) ] / (Dur10 - Dur5)
- Worked Q4 2026 5y5y Zero-Coupon Inflation Swap & PCE Translation:
- Exact Compounded 5y5y ZCIS = [ (1.0256)^10 / (1.0253)^5 ]^(0.20) - 1 = (1.2876 / 1.1331)^(0.20) - 1 = 2.590% (259.0 bps)
- Less DKW 5y5y Inflation Risk Premium (-30 bps) - Long-Run CPI-vs-PCE Wedge (-25 bps) = 2.04% Implied Long-Run PCE!
Exact 5y5y Zero-Coupon Compounded Forward & Swap-TIPS Basis Equations#
Comparing 5y5y ZCIS (259 bps) against 5y5y Cash TIPS (241 bps) separates true FOMC credibility shifts (both move together!) from dealer balance-sheet stress (cash drops while ZCIS holds steady!).
Historical Regime Signals: 5y5y Swap vs Cash TIPS Forward Matrix#
Notice March 2020: cash 5y5y TIPS breakevens crashed to 142 bps as levered funds liquidated cash TIPS for USD cash on FINRA TRACE, while 5y5y ZCIS held much firmer—proving the crash was a repo liquidity event, not deflation expectations!
| 5y5y Regime Reading (ZCIS) | Cash 5y5y TIPS Behavior | Economic Interpretation | Historical Precedent | FOMC Policy Reaction |
|---|---|---|---|---|
245 - 265 bps (Sweet Spot) | 225 - 245 bps (+18bp Basis) | Anchored at ~2.0% PCE + normal IRP | 2004-07 & 2025-2026 | Neutral; focuses on labor/supercore |
> 280 bps (Unanchoring Up) | > 260 bps (Both Surge!) | De-anchoring inflation risk premium | April 2022 (75bp Hikes) | Hawkish 50-75bp FOMC tightening |
< 200 bps (Disinflation Scare) | 175 - 190 bps (Parallel Drop) | Secular stagnation / weak demand | Feb 2016 Oil/China Shock | Dovish pause or QE readiness |
| 245 bps ZCIS / 155 bps TIPS! | Basis Blows Out to +90 bps! | Pure Cash TIPS Repo Fire Sale | March 2020 COVID Dash-for-Cash | Fed buys cash TIPS in SOMA (+85bp snapback!) |
Trading the 5y5y Swap-vs-TIPS Basis ("Forward Iota Box")#
Relative-value rates pods execute Forward 5y5y Iota Boxes: going Long 5y5y Cash TIPS Breakevens (241 bps) against Receiving Fixed 5y5y ZCIS (259 bps) whenever the forward swap-TIPS wedge widens past +24 bps (90th percentile). Because both legs reference identical NSA CPI-U indexation in Years 6-10 without front-end carry noise, the box isolates pure forward dealer balance-sheet normalization regulated across SEC and CFTC clearinghouses.
Cross-market desks pair these thresholds with TIPS Breakevens, CPI Shelter Persistence & Forward Real Rates, BLS CPI Shelter Persistence, and 1Y & 2Y Zero-Coupon Inflation Swaps inside our TIPS Breakevens archive and covered institutions directory.
Frequently asked questions
Why is 255-260 bps on the 5y5y CPI Swap considered consistent with the Fed’s 2.00% inflation target?
Inflation swaps reference Headline CPI-U, which runs ~25-30 bps above BEA PCE over decades due to Laspeyres formula/shelter weights, PLUS bond investors demand ~25-30 bps of positive forward Inflation Risk Premium (200 + 28 + 30 = 258 bps).
Where does the FRED series "T5YIFR" come from and is it based on swaps or cash TIPS?
St. Louis Fed’s popular T5YIFR series is calculated from nominal and cash TIPS Treasury constant-maturity yield curves (5y5y cash breakeven), NOT zero-coupon swaps—meaning T5YIFR can dip artificially during cash TIPS liquidity squeezes!
Who are the natural sellers (floating CPI payers) of 10-year and 30-year Zero-Coupon Inflation Swaps?
Regulated utilities, toll-road/infrastructure operators with CPI-escalated revenues, real-estate funds, and relative-value dealers warehousing hedged cash TIPS auctions supply CPI inflation on swaps against pension LDI fixed payers.
Why shouldn’t you compute cash 5y5y breakevens as simply 2 * 10Y_BEI - 5Y_BEI?
Coupon payments give a 10-year TIPS a duration closer to 8.9 years rather than 10.0 years; 2 * 10Y - 5Y slightly misweights the front 5 years unless computed off Gurkaynak-Sack-Wright fitted zero-coupon real and nominal curves.
Publication record
- Published
- November 13, 2026
- Updated
- November 14, 2026
- Author
- Dr. Marcus Vance, CFA
- Review
- Review not recorded
- Automated fact check
- Passed in the stored pipeline record
- Source URLs
- 3 recorded
AI assistance recorded: anthropic/claude-opus-4.6. This field does not establish human review or source verification.
Academic & Institutional Attribution
Cite This Research & Embed Live Data Card
Standard academic & institutional research paper citation format.
Dr. Marcus Vance, CFA. (2026, November 14). 5y5y Forward Inflation Swaps vs TIPS Breakevens: Stripping Out Oil & Liquidity Noise. AlphaPulse Finance. https://alphapulsefin.com/analysis/five-year-five-year-forward-inflation-swaps-tips-liquidityRelated Inflation Breakevens Real Rates & Institutional Briefings
Explore Inflation Breakevens Real Rates Hub (20) →Inflation Breakevens Real Rates
TIPS Breakevens, CPI Shelter Persistence & Forward Real Rates: Institutional GuideInflation Breakevens Real Rates
BLS CPI Shelter Persistence: 6-Month OER Panel Rotation vs New-Tenant Repeat Rent LagsInflation Breakevens Real Rates
BEA Core PCE vs BLS Core CPI Wedge: Scope, Weight & Fisher Substitution DecompositionInflation Breakevens Real Rates
TIPS Par Deflation Floor Convexity: Pricing Embedded 0% Put Options Across Issue VintagesInflation Breakevens Real Rates
10-Year TIPS Real Yields & S&P 500 Forward P/E Compression: Equity Duration RegimesInflation Breakevens Real Rates
NSA CPI 3-Month Indexation Lag & Front-End TIPS Seasonal Carry/Roll MechanicsInflation Breakevens Real Rates
Cleveland Fed Trimmed-Mean & Median CPI vs Dallas Fed Trimmed PCE: Outlier-Filtered SignalsInflation Breakevens Real Rates
1Y & 2Y Zero-Coupon Inflation Swaps: RBOB Gasoline Crack Spreads & WTI Pass-ThroughInstitutional Earnings Capex Macro
Hyperscaler AI GPU Useful-Life Accounting: 4-to-6-Year Server Depreciation Cliffs & EBIT RiskInstitutional Earnings Capex Macro
SEC Rule 10b5-1 Buyback Amendments & Quarterly Earnings Blackout Liquidity WindowsInstitutional Earnings Capex Macro
The S&P 500 Net Interest Expense Paradox: 3.1% Fixed Bonds vs 3.9% T-Bill Cash ShieldsInstitutional Earnings Capex Macro
S&P 500 Free Cash Flow Conversion Audit: Adjusting Operating Cash Flow for SBC & AI Capex
AlphaPulse Finance Data, Benchmarks & Contributor Records
CC BY 4.0 Open Data
Open Institutional Datasets (CSV / JSON) →
Download desk-compiled quantitative series & schemas.
2026 Reference Matrix
2026 Institutional Benchmarks & Thresholds →
Statutory capital, clearing, margin & rate conventions.
Editorial Records
Authors & Review Records →
View named contributors where those records are available.
Complete Index
Master Research & Dossier Archive →
Browse all published briefings by topic pillar & date.