
Inflation Breakevens Real Rates
TIPS Par Deflation Floor Convexity: Pricing Embedded 0% Put Options Across Issue Vintages
By statutory design, US TIPS redeem at the greater of inflation-adjusted principal or original $100 par—making newly auctioned TIPS with Index Ratios near 1.005 worth 4 to 11 bps tighter in real yield than seasoned high-accrual neighbors.
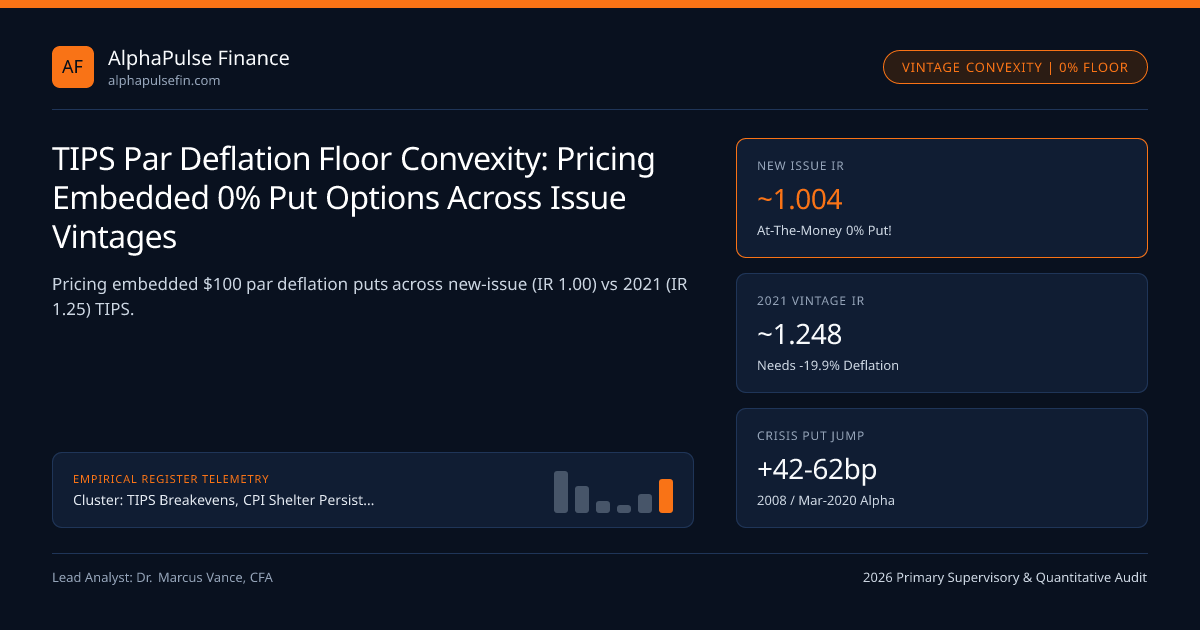
Hidden inside 31 CFR Part 356 Uniform Offering Circular rules is an asymmetric derivative gift from the US Treasury to bondholders: while semiannual TIPS coupons scale both up AND down with the Consumer Price Index, final maturity principal is legally floored at 100.00% of original par (Index Ratio >= 1.00000)! That statutory Par Deflation Floor embeds a zero-strike European CPI put option inside every 10-Year US TIPS under the TIPS-10Y-REAL 2026 Standard—generating rich relative-value kinks between newly auctioned TIPS (at-the-money floor!) and seasoned 2021 TIPS maturing the exact same year (24% out-of-the-money floor!).
Why Two TIPS Maturing Six Months Apart Trade at Different Real Yields!#
Compare two US TIPS trading side by side on FINRA TRACE with nearly identical remaining maturity (5.0 years):
- Bond A (Seasoned 10-Year TIPS Issued in Jan 2021, Maturing Jan 2031): Because cumulative US CPI rose +24.8% between 2021 and 2026, Bond A carries an Index Ratio of 1.24800 ($124.80 accrued principal per $100 original par). For Bond A's $100 par floor to pay off at maturity in 2031, cumulative US prices would have to fall by more than -19.9% (1 / 1.248 - 1)—a Great Depression catastrophe with <0.3% risk-neutral probability! Its deflation floor is virtually worthless (~0.2 bps).
- Bond B (Brand-New 5-Year TIPS Issued in Oct 2026, Maturing Oct 2031): Issued against current 2026 Base CPI, Bond B starts life with an Index Ratio of 1.00400! Any net cumulative deflation (<0.0% CPI) over the next five years puts Bond B's floor immediately in the money—making Bond B trade 4.5 to 9.5 bps LOWER in real yield (richer!) than Bond A!
How Deflation Panics (2008 & March 2020) Cause Vintage Basis to Explode +45 Bps#
In calm 2.3% inflation regimes, the yield discount on newly issued low-Index-Ratio TIPS sits quietly at 4 to 7 bps. Watch what happens when crude oil collapses and recession panic strikes (November 2008 or March 2020):
As 5-year breakevens plunge toward 0.15% and CPI option implied volatility doubles, the at-the-money deflation put inside the newly issued 5-year TIPS (IR = 1.002) explodes in Black-Scholes option vega and delta! During autumn 2008 and March 2020, primary dealers like Cantor Fitzgerald saw newly issued 5-year TIPS trade 38 to 62 bps richer in real yield than seasoned 10-year TIPS maturing in the exact same calendar window—delivering massive mark-to-market alpha to relative-value desks holding "New-vs-Old" matched-maturity TIPS boxes!
- RequiredCumulativeDeflationforPayoff = (BaseCPIIssue / CurrentRefCPIt) - 1 = (1 / IndexRatio_t) - 1
- Worked Oct-2031 New 5Y TIPS (IR = 1.004) vs Jul-2031 Old 10Y TIPS (IR = 1.230) Switch:
- Old 2031 TIPS Trades at 1.910% Real Yield (Floor Strike = -18.7% CPI -> Option Value = 0.2 bps -> Clean Real = 1.912%)
- New 2031 TIPS Fair Real Yield = 1.912% Clean Real - 0.064% (6.4 bps ATM 5Y Floor) = 1.848% Real Yield!
- If Auction Clears New 5Y at 1.890%: Buy New / Short Old locks in 6.2 bps of free deflation put for just 2.0 bps give-up!
Bachelier / Black-76 Embedded Deflation Floor Valuation Equations#
Stripping the exact option value of max(1, RefCPIT / BaseCPIIssue) using OTC 0%-strike Zero-Coupon Inflation Floors cleared/quoted across CFTC dealers yields "Floor-Adjusted Clean Real Yields" across the entire TIPS curve.
Matched-Maturity Seasoned vs New-Issue TIPS Vintage Matrix (Q4 2026)#
Remember also the tax & coupon cash-flow nuance for taxable accounts on wealth platforms like Ally Invest: positive annual CPI principal accretion is taxed annually as "phantom OID income" under IRC §1275 unless held in tax-exempt accounts (whereas negative CPI years generate tax deductions up to prior inclusions!).
| Matched-Maturity TIPS Pair | Issue Date & Original Tenor | Q4 2026 Index Ratio | Deflation Needed to Hit Floor | Embedded Floor Yield Value |
|---|---|---|---|---|
| Oct 2031 New 5-Year TIPS | Oct 2026 (5-Year New) | 1.00412 | -0.41% (At-The-Money!) | 6.4 bps (High Tail Vega) |
| Jul 2031 Old 10-Year TIPS | Jul 2021 (10-Year Old) | 1.22950 | -18.67% (Deep OTM) | 0.2 bps (Zero Put Value) |
| Jul 2036 New 10-Year TIPS | Jul 2026 (10-Year New) | 1.00980 | -0.97% (10Y Horizon) | 3.1 bps (22% Drift Hurdle) |
| Feb 2042 Old 30-Year TIPS | Feb 2012 (30-Year Old) | 1.41200 | -29.18% (Impossible) | 0.0 bps (Pure Real Duration) |
Constructing DV01-Neutral "Cheap Deflation Put" TIPS Vintage Switches#
Whenever a fresh April or October 5-Year TIPS New Issue prices at Treasury auction with a Real Yield concession within 2.0 bps of the seasoned 10-year TIPS maturing in the same year, relative-value pods Buy the New 5Y TIPS (IR ~ 1.00) and Short the Seasoned Old 10Y TIPS (IR ~ 1.25) hedged for minor coupon-duration differences against 10-Year Nominal Notes. You acquire a 5-year at-the-money US deflation tail put for <=2 bps/yr, owning explosive +40-bps convex upside in any hard-landing deflation scare!
Adjacent curve and flow decompositions include 10-Year TIPS Real Yields & S&P 500 Forward P/E Compression and 30-Year TIPS Real Yield Auctions, anchored by TIPS Breakevens, CPI Shelter Persistence & Forward Real Rates, TIPS Breakevens, and quantitative methodology.
Frequently asked questions
Are semiannual TIPS interest coupon payments protected by the 0% deflation floor if CPI falls?
No! Only final principal repayment at stated maturity is floored at $100 par. If the Index Ratio drops to 0.96 during Year 2, semiannual coupons are paid on $96.00 of principal (Real Coupon * 0.96), before principal snaps back to >=$100 at maturity.
Why is the deflation floor worth MORE bps per year on a newly issued 5-Year TIPS than on a newly issued 30-Year TIPS?
Positive expected inflation drift (+2.2%/yr) pushes cumulative CPI ~+92% higher over 30 years—making cumulative 30-year net deflation (<0%) extremely unlikely compared to a sharp 3-to-5-year recessionary deflation shock!
How does the NY Fed’s DKW model handle the embedded deflation floor when estimating TIPS liquidity?
Before fitting smooth real yield curves, Fed and dealer splines subtract the Black-76 / Bachelier value of each bond’s specific Index Ratio put (marked to OTC zero-coupon 0% CPI floors) so vintage kinks don’t distort real yields.
What happens to a stripped TIPS Principal STRIP versus Coupon STRIP in deflation?
Under 31 CFR 356.31, the statutory $100 par deflation floor stays attached exclusively to the TIPS Principal STRIP (PO), which is why different vintages of TIPS Principal STRIPs are NOT fungible with one another!
Publication record
- Published
- November 13, 2026
- Updated
- November 14, 2026
- Author
- Dr. Marcus Vance, CFA
- Review
- Review not recorded
- Automated fact check
- Passed in the stored pipeline record
- Source URLs
- 3 recorded
AI assistance recorded: anthropic/claude-opus-4.6. This field does not establish human review or source verification.
Academic & Institutional Attribution
Cite This Research & Embed Live Data Card
Standard academic & institutional research paper citation format.
Dr. Marcus Vance, CFA. (2026, November 14). TIPS Par Deflation Floor Convexity: Pricing Embedded 0% Put Options Across Issue Vintages. AlphaPulse Finance. https://alphapulsefin.com/analysis/tips-par-deflation-floor-embedded-put-convexity-vintagesRelated Inflation Breakevens Real Rates & Institutional Briefings
Explore Inflation Breakevens Real Rates Hub (20) →Inflation Breakevens Real Rates
TIPS Breakevens, CPI Shelter Persistence & Forward Real Rates: Institutional GuideInflation Breakevens Real Rates
10-Year TIPS Real Yields & S&P 500 Forward P/E Compression: Equity Duration RegimesInflation Breakevens Real Rates
NSA CPI 3-Month Indexation Lag & Front-End TIPS Seasonal Carry/Roll MechanicsInflation Breakevens Real Rates
Cleveland Fed Trimmed-Mean & Median CPI vs Dallas Fed Trimmed PCE: Outlier-Filtered SignalsInflation Breakevens Real Rates
1Y & 2Y Zero-Coupon Inflation Swaps: RBOB Gasoline Crack Spreads & WTI Pass-ThroughInflation Breakevens Real Rates
D’Amico-Kim-Wei (DKW) Model: Separating TIPS Liquidity Premia From Inflation Risk PremiaInflation Breakevens Real Rates
Core PCE Imputed Financial Services & Portfolio Management Fees: S&P 500 Equity Beta in InflationInflation Breakevens Real Rates
30-Year TIPS Real Yield Auctions: February/August Supply Liquidity & Real-Annuity LDI DemandInstitutional Earnings Capex Macro
S&P 500 Free Cash Flow Conversion Audit: Adjusting Operating Cash Flow for SBC & AI CapexInstitutional Earnings Capex Macro
Hyperscaler Data-Center Power Bottlenecks: Grid Interconnection Queues, Nuclear PPAs & HPC LandlordsInstitutional Earnings Capex Macro
IRC Section 4501 1% Buyback Excise Tax & Accelerated Share Repurchase (ASR) Dealer CollarsInstitutional Earnings Capex Macro
Consensus EPS Revision Breadth & SEC Reg FD Preannouncements: Modeling the +3.8% "Beat" Game
AlphaPulse Finance Data, Benchmarks & Contributor Records
CC BY 4.0 Open Data
Open Institutional Datasets (CSV / JSON) →
Download desk-compiled quantitative series & schemas.
2026 Reference Matrix
2026 Institutional Benchmarks & Thresholds →
Statutory capital, clearing, margin & rate conventions.
Editorial Records
Authors & Review Records →
View named contributors where those records are available.
Complete Index
Master Research & Dossier Archive →
Browse all published briefings by topic pillar & date.