
Treasury Quarterly Refunding Coupon Supply & TBAC Weighted Average Maturity Limits
Quarterly Refunding Announcements holding benchmark 10-year new issues at $42B and 30-year bonds at $25B push T-bill share toward 21.8% as Treasury balances macro term premia against weighted-average maturity rollover risk.
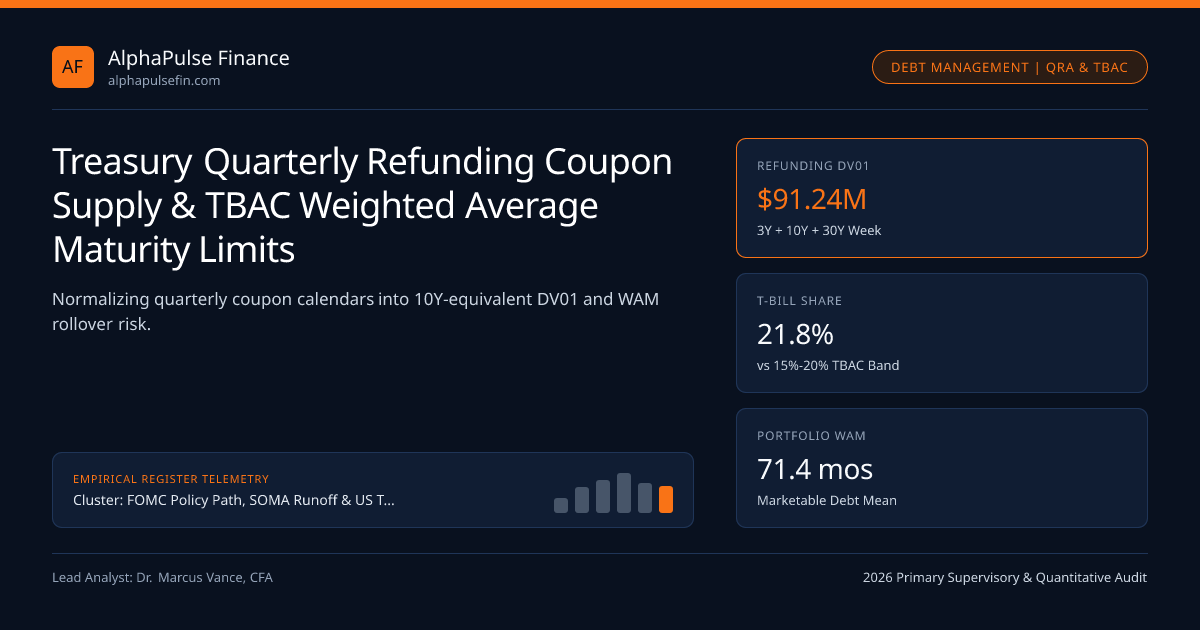
Every February, May, August, and November, the US Department of the Treasury's Quarterly Refunding Announcement (QRA) establishes the deterministic supply trajectory of nominal coupons, Floating Rate Notes (FRNs), and TIPS that primary dealers must underwrite. With monthly new-issue sizes stabilized near $69B in 2-year notes, $70B in 5-year notes, $42B in 10-Year Benchmark Notes, and $25B in 30-Year Long Bonds, the sovereign debt stock's weighted-average maturity (WAM) hovers near 71.4 months while Treasury bills account for 21.8% of marketable debt—above the Treasury Borrowing Advisory Committee's (TBAC) traditional 15%-20% target range.
Regular and Predictable Issuance Philosophy vs Active Maturity Tilting#
Since the 1970s, US debt management has adhered to a "regular and predictable" auction framework designed to minimize sovereign borrowing costs over multi-decade cycles rather than timing short-term yield fluctuations. Abrupt jumps in coupon auction sizes—such as the August 2023 QRA step-up that drove 10-year yields roughly 75 bps higher over ten weeks—demonstrated that long-end term premia exhibit non-linear sensitivity to unexpected 10-year-equivalent DV01 supply.
When Treasury holds nominal coupon sizes steady across subsequent quarters while federal net borrowing remains near $1.95 trillion annually, residual financing deficits automatically flow into 4-week, 8-week, 13-week, 17-week, 26-week, and 52-week T-bills alongside TGA Cash Balance management bills. Money market funds readily absorb front-end bills near 3.90% without demanding duration concessions, effectively capping 10s30s steepening at the expense of higher annual rollover frequency.
Converting Nominal Coupon Schedules into 10-Year-Equivalent DV01 Load#
Raw dollar issuance misstates true duration burden because $69 billion of 2-year notes carries roughly one-fourth the interest-rate sensitivity of $42 billion of 10-year notes and less than one-ninth the modified duration of $25 billion of 30-year bonds. Institutional desks normalize every QRA calendar into 10-year-equivalent supply (assuming an 8.15-year modified duration per $100 par on the current 4.32% 10-year note).
Across FY 2026, gross private coupon issuance after accounting for SOMA redemptions delivers approximately $2.38 trillion in 10-year-equivalent duration to private balance sheets, equal to $1.94 billion of DV01 per year that asset managers, insurance companies, and primary dealers such as Cantor Fitzgerald must digest under FINRA and Federal Reserve reporting rules.
- AuctionDV01k = Notionalk * ModDurk * 0.0001
- Worked Refunding Week Calculation (3Y $58B + 10Y $42B + 30Y $25B):
- 3Y Note DV01 (ModDur 2.76): $58B * 2.76 * 0.0001 = $16.01M
- 10Y Note DV01 (ModDur 8.15): $42B * 8.15 * 0.0001 = $34.23M
- 30Y Bond DV01 (ModDur 16.40): $25B * 16.40 * 0.0001 = $41.00M
- Total 3-Day Refunding DV01 = $91.24M (= $111.95B in 10-Year-Equivalent Supply)
WAM Trajectory and Rollover Cost Sensitivity Modeling#
Debt managers evaluate a formal cost-at-risk trade-off: shortening WAM from 71.4 months toward 64 months lowers immediate coupon service when the yield curve is upward-sloping (+44 bps 2s10s), but exposes the federal budget to rapid interest-expense pass-through if an inflation shock forces the FOMC back above 4.75%.

Refunding Tenor Matrix and Institutional Absorption Profile#
Different maturity buckets rely on segmented buyer cohorts tracked across custody accounts, SEC Form N-MFP filings, and broker-dealer platforms including Ally Invest.
| Benchmark Tenor | Refunding Auction Size | Modified Duration | DV01 per Issue | Primary Institutional Buyer & Oversight |
|---|---|---|---|---|
| 2-Year Note | $69.0B Monthly | 1.88 yrs | $12.97M | FX Reserve Managers & Corporate Cash (SEC 2a-7) |
| 5-Year Note | $70.0B Monthly | 4.46 yrs | $31.22M | Bank HQLA Portfolios (OCC LCR Level 1) |
| 10-Year Note (UST-QRA-10Y) | $42.0B Refunding | 8.15 yrs | $34.23M | Multi-Asset & Cash-Futures Desks (Cantor) |
| 30-Year Bond (UST-QRA-30Y) | $25.0B Refunding | 16.40 yrs | $41.00M | Corporate DB Pensions & Life Insurers (FINRA TRACE) |
Trading QRA Financing Estimates vs Wednesday Policy Statements#
Refunding weeks split market-moving information across two releases: Monday 3:00 PM ET marketable borrowing estimates (total dollar need and quarter-end TGA assumption) and Wednesday 8:30 AM ET coupon auction tables plus TBAC charge responses. Rates desks fade Monday headline borrowing surprises when driven solely by TGA cash-buffer adjustments, reserving duration hedges for Wednesday shifts in 10Y, 20Y, and 30Y auction guidance.
Broader structural context is documented in FOMC Policy Path, SOMA Runoff & US Treasury Term Premia, with granular extensions in 10-Year US Treasury Auction Tails, Indirect and US Treasury Liquidity-Support Buybacks across FOMC Policy Path and institutional datasets.
Frequently asked questions
Why does TBAC recommend keeping US Treasury bills between 15% and 20% of marketable debt?
TBAC models show a 15%-20% bill share balances lower average front-end yields and deep money-market liquidity against fiscal rollover risk, preventing short-rate spikes from immediately repricing federal interest outlays.
What is 10-year-equivalent Treasury supply and why do rates desks prefer it over dollar par volume?
Ten-year-equivalent supply weights each maturity by its modified duration relative to the 10-year benchmark (ModDur_k / 8.15), capturing actual market-price risk (DV01) rather than misleading face-value totals dominated by short bills.
How do SOMA redemptions affect net private coupon supply in QRA forecasts?
When SOMA lets maturing notes run off up to its monthly redemption cap instead of rolling them as non-competitive add-ons at auction, Treasury must increase public issuance to raise the cash needed to pay back the Federal Reserve.
Why did Treasury cut 20-year bond auction sizes disproportionately after 2021?
Structural end-user demand from pensions and insurers concentrates at the 10-year and 30-year points, leaving the re-introduced 20-year bond chronically cheap by 12 to 22 bps on fitted splines until Treasury scaled back supply.
Publication record
- Published
- November 14, 2026
- Updated
- November 14, 2026
- Author
- Dr. Marcus Vance, CFA
- Review
- Review not recorded
- Automated fact check
- Passed in the stored pipeline record
- Source URLs
- 3 recorded
AI assistance recorded: anthropic/claude-opus-4.6. This field does not establish human review or source verification.
Academic & Institutional Attribution
Cite This Research & Embed Live Data Card
Standard academic & institutional research paper citation format.
Dr. Marcus Vance, CFA. (2026, November 14). Treasury Quarterly Refunding Coupon Supply & TBAC Weighted Average Maturity Limits. AlphaPulse Finance. https://alphapulsefin.com/analysis/quarterly-refunding-coupon-supply-tbac-weighted-average-maturityRelated Fomc Treasury Term Premium & Institutional Briefings
Explore Fomc Treasury Term Premium Hub (20) →Fomc Treasury Term Premium
FOMC Policy Path, SOMA Runoff & US Treasury Term Premia: Institutional Rates GuideFomc Treasury Term Premium
10-Year US Treasury Auction Tails, Indirect Bidder Takedown & When-Issued ConcessionFomc Treasury Term Premium
30-Year Treasury Bond Auction Liquidity, Convexity Hedging & Pension LDI AbsorptionFomc Treasury Term Premium
2-Year Treasury Note Auctions vs Overnight Index Swaps: Front-End FOMC Policy PricingFomc Treasury Term Premium
FOMC SEP Dot-Plot Dispersion & Longer-Run Median Drift: Committee Reaction UncertaintyFomc Treasury Term Premium
Holston-Laubach-Williams vs Lubik-Matthes Neutral Rate (r*) Estimation in US RatesFomc Treasury Term Premium
SOMA Monthly Redemption Caps, MBS Prepayment Drag & Secondary T-Bill ReinvestmentFomc Treasury Term Premium
US Treasury Liquidity-Support Buybacks: Off-the-Run Spline Errors & Old/New 20Y-30Y SpreadsMarket Insights
Week Ahead for FX, Bonds: Fed Minutes, U.K. Data in FocusMarket Insights
U.S., Eurozone Bond Yields RiseMonetary Policy
Of all the ways Chairman Kevin Warsh wants to remake the Fed, the least flashy may be the most lasting: He is cutting the number of interest-rate decisions the central bank makes each yearMarket Insights
US FX: Dollar Strengthens; Emerging Markets Mixed
AlphaPulse Finance Data, Benchmarks & Contributor Records
CC BY 4.0 Open Data
Open Institutional Datasets (CSV / JSON) →
Download desk-compiled quantitative series & schemas.
2026 Reference Matrix
2026 Institutional Benchmarks & Thresholds →
Statutory capital, clearing, margin & rate conventions.
Editorial Records
Authors & Review Records →
View named contributors where those records are available.
Complete Index
Master Research & Dossier Archive →
Browse all published briefings by topic pillar & date.