Fedwire Securities Settlement Timing, Daylight Overdrafts & Intraday LCR Buffer Traps
Avoidance of uncollateralized 50-bps Federal Reserve daylight overdrafts and internal Resolution Liquidity Adequacy and Positioning (RLAP) buffers locks up $1.1T+ of intraday bank reserves.
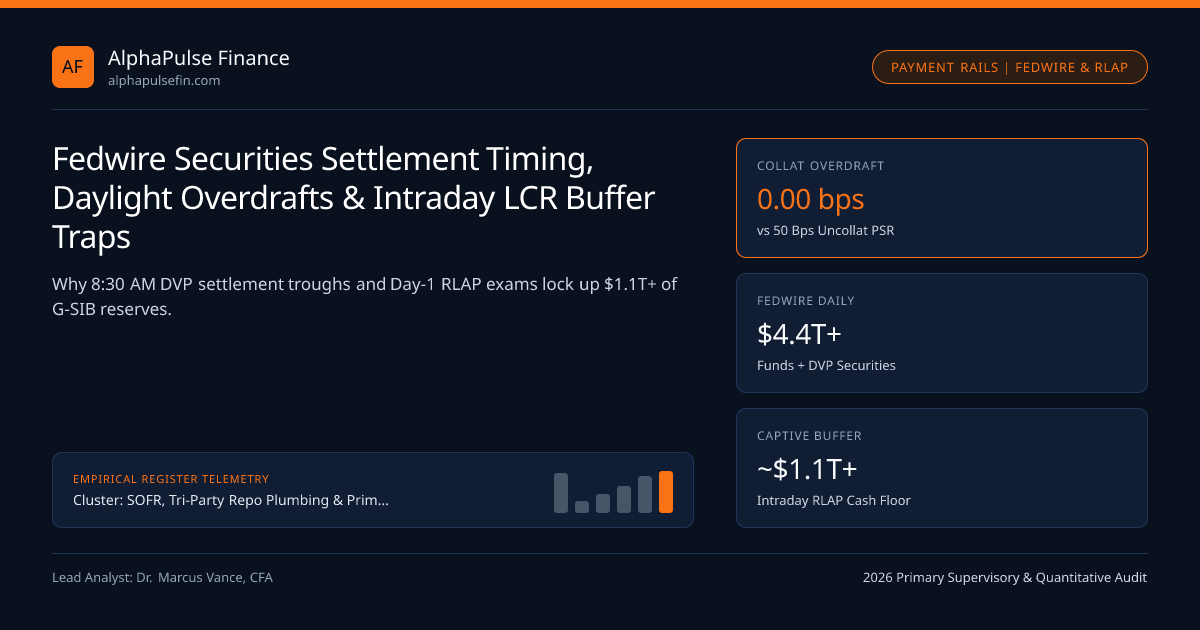
Why do US commercial banks insist on holding $3.12 trillion in SOMA Reserve Balances when both cash reserves and US Treasuries count equally as 0%-haircut Level 1 High-Quality Liquid Assets (HQLA) under the statutory 30-day Liquidity Coverage Ratio (LCR)? The answer lies inside 8:30 AM to 3:30 PM ET intraday settlement: while statutory LCR is measured only at end-of-day, internal Resolution Liquidity Adequacy and Positioning (RLAP) stress tests and avoidance of Federal Reserve Fedwire daylight overdrafts penalize Treasuries relative to instant Fedwire cash—driving early-morning SOFR friction unless unlocked by the Standing Repo Facility.
Fedwire Securities 8:30 AM Delivery-vs-Payment Burst vs Afternoon Cash Return#
Over $4.4 trillion clears daily across Fedwire Funds and Fedwire Securities, yet inflows and outflows inside a clearing bank's master account are acutely asynchronous:
- 8:30 AM - 10:30 AM ET Morning Drain: Fedwire Securities opens at 8:30 AM ET; newly issued US Treasury auction settlements and bilateral FICC DVP deliveries sweep instantaneously, debiting cash buyers' reserve balances by hundreds of billions within 45 minutes.
- 3:30 PM - 5:30 PM ET Afternoon Square-Up: Returning corporate wires, CHIPS net settlement, and late-day money market fund cash flows replenish bank accounts hours later.
Under the Federal Reserve Payment System Risk (PSR) Policy, uncollateralized Fedwire daylight overdrafts incur a 50-bps annualized fee (prorated over the 21.5-hour Fedwire day), whereas collateralized daylight overdrafts carry a 0.00% fee—yet supervisory stigma under OCC and FDIC intraday liquidity exams historically deterred banks from dipping into daylight credit at all!
RLAP "Day-1 Monetization" Limits: Why Treasuries Cannot Replace Cash 1:1#
Under Living Will Title I resolution planning (12 CFR Part 243) and Reg YY internal liquidity stress tests (ILST), G-SIBs must prove Resolution Liquidity Adequacy and Positioning (RLAP)—demonstrating enough instant Day-1 morning cash to survive catastrophic intraday wire runs before any Treasury securities could be sold or repoed in private markets.
Examiners place strict "monetization caps" on how many billions of Level 1 Treasuries a single megabank may assume it could repo privately with dealers like Cantor Fitzgerald on Day 1 of a systemic crisis without overwhelming market depth. Unless regulators grant full Day-1 RLAP monetization credit to pre-positioned SRF (4.00%) and Discount Window collateral, G-SIB treasurers hoard ~$1.1T+ of captive cash reserves that never enter private repo lending!
- UncollatDailyPSRFee = (UncollateralizedAvgOverdraft - 0.10 * RiskBasedCapital) * (0.0050 / 360) * (Hours_Open / 24)
- Worked Intraday Monetization Bottleneck ($120B G-SIB HQLA Portfolio vs $80B Day-1 RLAP Outflow Stress):
- Case A (Private Repo Cap = $30B/day): Bank MUST hold $80B - $30B = $50.0B in sterile Fed reserves!
- Case B (Supervisory Credit for $40B Pre-Positioned SRF + $30B Private):
- Required Captive Cash Reserves Drop to $80B - $70B = $10.0B -> Frees $40.0B for morning SOFR repo lending!
PSR Daylight Overdraft Fee Formula & Intraday Peak Liquidity Drain#
Quantifying intraday peak net debit positions explains why aggregate Fedwire payment timing (measured by the NY Fed's average time of 50th-percentile payment completion) drifts later into the afternoon whenever reserves tighten.
End-of-Day LCR vs Intraday RLAP / PSR Regulatory Treatment#
Comparing statutory 30-day LCR against internal Day-1 RLAP exposes the exact supervisory friction elevating the economy's Lowest Comfortable Level of Reserves.
| Liquidity Rule / Rail | Measurement Window | Cash Reserves Credit | On-the-Run UST Credit | Supervisory Authority |
|---|---|---|---|---|
| Liquidity Coverage Ratio (LCR) | End-of-Day (30d Horizon) | 100% Level 1 HQLA | 100% Level 1 HQLA | OCC / Federal Reserve / FDIC |
| Title I Living Will RLAP | Intraday Hour-by-Hour | 100% Instant Fedwire | Capped Without SRF | Federal Reserve & FDIC |
| Fed PSR Daylight Credit | Minute-by-Minute Balance | Zero Overdraft | 0 bps Fee If Pre-Pledged | Regional Reserve Banks |
| Broker-Dealer Rule 15c3-1 | Continuous Net Capital | 100% Good Capital | 98% - 99.5% After Haircut | SEC / FINRA (Cantor) |
Fedwire Funds 22x7x365 ISO 20022 Expansion & Settlement Velocity#
Following Fedwire Funds Service migration to ISO 20022 messaging and operational preparation toward extended 22-hour/weekend settlement alongside FedNow and real-time settlement rails like Bosonic, bank treasury ALM desks face weekend/overnight automated liquidity outflow risk—reinforcing structural preference for pre-pledged zero-fee Federal Reserve collateralized overdraft lines.
Multi-asset CIOs synthesize this factor alongside SOFR, Tri-Party Repo Plumbing & Primary Dealer Balance Sheets, Federal Reserve Discount Window Readiness, and SEC Rule 17ad-22(e)(6) Treasury Central Clearing Mandate via SOFR and covered institutions.
Frequently asked questions
If US Treasuries and Fed reserves are both Level 1 HQLA, why wont banks swap all reserves into higher-yielding Treasuries?
End-of-day LCR treats them equally, but intraday RLAP and Reg YY stress tests assume a megabank cannot liquidate or privately repo $50B+ of Treasuries before 10:00 AM ET on Day 1 of a systemic run—requiring instant Fedwire cash.
What is a Fedwire daylight overdraft and what does the Federal Reserve charge for it?
A daylight overdraft occurs when a bank’s Fed master account dips negative during the business day before incoming wires restore a positive closing balance; collateralized overdrafts cost 0 bps, while uncollateralized ones above a deductible cost 50 bps annualized.
How do NY Fed economists detect hidden intraday reserve scarcity from Fedwire timestamps?
When reserves grow tight, banks delay sending outgoing Fedwire payments until they receive incoming wires from counterparties—pushing the timestamp at which 50% of daily payment value clears steadily later past 1:45 PM ET.
What is RLAP in US G-SIB resolution planning?
Resolution Liquidity Adequacy and Positioning (RLAP) is a Dodd-Frank Title I Living Will requirement ensuring both the parent holding company and each material operating subsidiary hold enough localized intraday liquidity to enter resolution cleanly.
Publication record
- Published
- November 13, 2026
- Updated
- November 14, 2026
- Author
- Dr. Marcus Vance, CFA
- Review
- Review not recorded
- Automated fact check
- Passed in the stored pipeline record
- Source URLs
- 3 recorded
AI assistance recorded: anthropic/claude-opus-4.6. This field does not establish human review or source verification.
Academic & Institutional Attribution
Cite This Research & Embed Live Data Card
Standard academic & institutional research paper citation format.
Dr. Marcus Vance, CFA. (2026, November 14). Fedwire Securities Settlement Timing, Daylight Overdrafts & Intraday LCR Buffer Traps. AlphaPulse Finance. https://alphapulsefin.com/analysis/intraday-fedwire-daylight-overdrafts-liquidity-coverage-ratioRelated Sofr Repo Funding Liquidity & Institutional Briefings
Explore Sofr Repo Funding Liquidity Hub (20) →Sofr Repo Funding Liquidity
SOFR, Tri-Party Repo Plumbing & Primary Dealer Balance Sheets: Money Market GuideSofr Repo Funding Liquidity
Federal Reserve Discount Window Readiness: Pre-Positioned Collateral Valuation & HaircutsSofr Repo Funding Liquidity
ARRC CME Term SOFR Scope Restrictions: Compounded SOFR in Arrears vs Cash Loan ConventionsSofr Repo Funding Liquidity
SOFR vs EFFR & IORB Corridor Spreads: Measuring Reserve Demand Elasticity Near ScarcitySofr Repo Funding Liquidity
ON RRP Facility Drainage & Rule 2a-7 Money Market Fund Rotation into Short T-BillsSofr Repo Funding Liquidity
NY Fed Standing Repo Facility (SRF) Usage: Auction Timing, Tri-Party Settlement & StigmaSofr Repo Funding Liquidity
DTCC FICC Sponsored DVP Repo: Multilateral Netting & ASC 210-20 Balance Sheet ReliefSofr Repo Funding Liquidity
SEC Rule 17ad-22(e)(6) Treasury Central Clearing Mandate: Done-With vs Done-Away MarginCorporate Credit Spread Cycles
Out-of-Court Distressed Debt Exchanges vs Prepackaged Chapter 11: The 38% Re-Default TrapCorporate Credit Spread Cycles
Reverse Yankee Corporate Bond Issuance: EUR/USD Cross-Currency Basis & ECB-Fed ArbitrageInflation Breakevens Real Rates
5y5y Forward Inflation Swaps vs TIPS Breakevens: Stripping Out Oil & Liquidity NoiseInflation Breakevens Real Rates
BLS CPI Shelter Persistence: 6-Month OER Panel Rotation vs New-Tenant Repeat Rent Lags
AlphaPulse Finance Data, Benchmarks & Contributor Records
CC BY 4.0 Open Data
Open Institutional Datasets (CSV / JSON) →
Download desk-compiled quantitative series & schemas.
2026 Reference Matrix
2026 Institutional Benchmarks & Thresholds →
Statutory capital, clearing, margin & rate conventions.
Editorial Records
Authors & Review Records →
View named contributors where those records are available.
Complete Index
Master Research & Dossier Archive →
Browse all published briefings by topic pillar & date.