
EUR/USD & USD/JPY Cross-Currency Basis Swaps: Offshore Synthetic Dollar Funding vs SOFR
Persistent -18 bps EUR/USD and -26 bps USD/JPY cross-currency basis spreads reflect offshore synthetic dollar demand across $95T+ of global FX swaps relative to domestic SOFR.
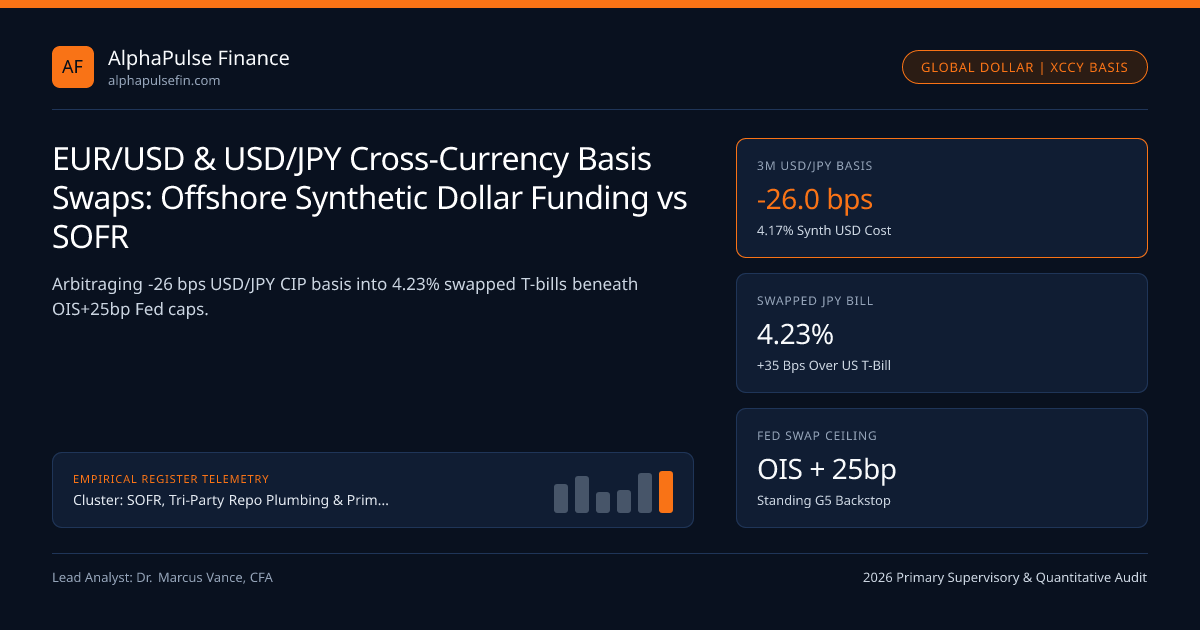
More than $95 trillion of off-balance-sheet FX forwards, FX swaps, and cross-currency basis swaps tracked by the Bank for International Settlements (BIS) synthetically fund global dollar portfolios outside the United States. Because non-US insurers, pensions, and corporate treasurers lack direct access to domestic SOFR Repo (3.91%), they pledge local EUR or JPY cash to global G-SIB dealers in exchange for dollars—driving a persistent Covered Interest Parity (CIP) violation where synthetic offshore USD funding costs +18 bps (EUR/USD basis = -18 bps) to +26 bps (USD/JPY basis = -26 bps) above domestic SOFR, capped only by the Federal Reserve System standing central bank liquidity swap lines.
Quotation Convention: Why a Negative Basis Means Expensive Dollars#
In modern post-LIBOR Risk-Free Rate (RFR) cross-currency basis swaps cleared and reported under CFTC SDR rules, one counterparty borrows USD paying compounded SOFR flat and lends foreign currency receiving compounded ESTR (EUR) or TONAR (JPY) plus the basis spread alpha.
When alpha = -26 bps on 3-month USD/JPY:
- A Japanese mega-bank borrowing USD must accept TONAR minus 26 bps on the yen collateral it hands over—equivalent to paying SOFR + 26 bps (~4.17%) for synthetic dollars!
- Conversely, a US dollar cash-rich asset manager or sovereign wealth fund swapping USD into JPY to buy 3-month Japanese T-Bills (T-DBs) earns the local JPY bill yield plus the +26 bps basis pickup—generating SOFR + 28 to +36 bps in risk-free dollar-hedged carry through dealers like Cantor Fitzgerald and cross-border FX infrastructure such as Airwallex and Capitals Gain!
Dealer SLR Shadow Cost + Standing Central Bank Swap Line Ceiling#
Before 2008, textbook arbitrage eliminated CIP deviations beyond +/-2 bps within minutes. Post-Basel III, however, FX swaps generate SA-CCR derivative leverage exposure and on-balance-sheet cash leg expansion for G-SIB bank dealers supervised by the Federal Reserve and OCC—requiring a 15-to-30 bps CIP wedge before banks commit balance sheet.
What prevents the 3-month EUR/USD or USD/JPY basis from blowing out to -150 bps during macro panics? Standing bilateral Central Bank Dollar Liquidity Swap Lines linking the Federal Reserve with the ECB, Bank of Japan, Bank of England, Swiss National Bank, and Bank of Canada (OSFI banks) lend 7-day USD at SOFR OIS + 25 bps—establishing an official offshore ceiling around -30 to -40 bps!
- USDSwappedForeignBill = YForeignBill3M + (RSOFR3M - RForeignOIS3M) - BasisXCCY_3M
- Worked 3-Month Swapped Japanese T-Bill (T-DB) Pickup for USD Cash Portfolio:
- 3M Japan T-DB Yield: 0.81% | 3M TONAR OIS: 0.75% (+6 bps local bill spread)
- 3M USD SOFR OIS: 3.91% | 3M USD/JPY Basis: -0.26% (-26 bps)
- All-In USD-Hedged Return = 0.81% + (3.91% - 0.75%) - (-0.26%) = 0.81% + 3.16% + 0.26% = 4.23%!
- Net Riskless Alpha Over 3.88% US T-Bill = 4.23% - 3.88% = +35.0 bps annualized
Covered Interest Parity Deviation & Synthetic JPY T-Bill Arbitrage Math#
Computing exact dollar-hedged returns on Japanese Treasury Discount Bills (T-DBs) illustrates one of institutional cash management's highest Sharpe-ratio sovereign trades.
G5 Cross-Currency Basis & Offshore Dollar Ceiling Matrix (Q4 2026)#
Basis spreads vary across currencies according to whether the local banking sector is structurally net-short USD assets (Japan, Eurozone) or net-long/balanced (Australia, UK).
| G5 Currency Pair | 3M RFR XCCY Basis | 5Y RFR XCCY Basis | Implied Synth USD Cost | Central Bank Backstop & Venue |
|---|---|---|---|---|
| EUR / USD (ESTR vs SOFR) | -18.0 bps | -24.5 bps | 4.09% (SOFR + 18bp) | ECB Weekly 7d USD (CFTC SEF) |
| USD / JPY (TONAR vs SOFR) | -26.0 bps | -41.0 bps | 4.17% (SOFR + 26bp) | Bank of Japan USD Ops (Cantor) |
| GBP / USD (SONIA vs SOFR) | -9.5 bps | -14.0 bps | 4.005% (SOFR + 9.5bp) | Bank of England Swap Line |
| USD / CAD (CORRA vs SOFR) | -11.0 bps | -16.5 bps | 4.02% (SOFR + 11bp) | Bank of Canada / OSFI |
Year-End Turn Asymmetry in 1-Month FX Forward Points#
Whenever 3-month FX swaps roll across September 30 or December 31 (specifically in late September for Q4 3-month swaps!), cross-currency basis widens abruptly by an extra -12 to -28 bps overnight as European and Japanese banks lock in year-end dollar funding simultaneously—leading domestic SOFR SR1 turn pricing by several weeks.
Compare parallel plumbing dynamics in Fedwire Securities Settlement Timing, Daylight Overdrafts and DTCC FICC Sponsored DVP Repo, framed by SOFR, Tri-Party Repo Plumbing & Primary Dealer Balance Sheets, SOFR, and analytical tools.
Frequently asked questions
Why did Covered Interest Parity (CIP) hold before 2008 and break permanently afterward?
Arbitraging CIP requires a bank dealer to borrow dollars on balance sheet and lend foreign currency via FX swaps; post-2008 Basel III SLR and SA-CCR capital rules charge ~20-30 bps of equity cost on that balance sheet expansion.
Why do central bank dollar swap lines price at SOFR OIS + 25 bps?
Lowered from OIS + 50 bps to OIS + 25 bps in March 2020, the +25 bps spread sits high enough to avoid crowding out private FX swaps in calm markets, yet low enough to cap global dollar funding stress immediately during crises.
Why is the 3-month cross-currency basis wider in USD/JPY (-26 bps) than GBP/USD (-9.5 bps)?
Japanese banks, insurers, and GPIF/trust accounts run one of the world’s largest structural net long USD asset imbalances requiring continuous rolling FX hedges, whereas London’s wholesale GBP/USD balance is far more two-way.
How does BIS measure "$95 trillion" of off-balance-sheet FX swap dollar debt?
Under accounting conventions, principal payment obligations on maturing FX forwards and swaps stay off the face of corporate and bank balance sheets despite requiring 100% gross cash dollar delivery at maturity.
Publication record
- Published
- November 13, 2026
- Updated
- November 14, 2026
- Author
- Dr. Marcus Vance, CFA
- Review
- Review not recorded
- Automated fact check
- Passed in the stored pipeline record
- Source URLs
- 3 recorded
AI assistance recorded: anthropic/claude-opus-4.6. This field does not establish human review or source verification.
Academic & Institutional Attribution
Cite This Research & Embed Live Data Card
Standard academic & institutional research paper citation format.
Dr. Marcus Vance, CFA. (2026, November 14). EUR/USD & USD/JPY Cross-Currency Basis Swaps: Offshore Synthetic Dollar Funding vs SOFR. AlphaPulse Finance. https://alphapulsefin.com/analysis/cross-currency-basis-swaps-fx-swap-implied-dollar-fundingRelated Sofr Repo Funding Liquidity & Institutional Briefings
Explore Sofr Repo Funding Liquidity Hub (20) →Sofr Repo Funding Liquidity
SOFR, Tri-Party Repo Plumbing & Primary Dealer Balance Sheets: Money Market GuideSofr Repo Funding Liquidity
Fedwire Securities Settlement Timing, Daylight Overdrafts & Intraday LCR Buffer TrapsSofr Repo Funding Liquidity
Federal Reserve Discount Window Readiness: Pre-Positioned Collateral Valuation & HaircutsSofr Repo Funding Liquidity
ARRC CME Term SOFR Scope Restrictions: Compounded SOFR in Arrears vs Cash Loan ConventionsSofr Repo Funding Liquidity
SOFR vs EFFR & IORB Corridor Spreads: Measuring Reserve Demand Elasticity Near ScarcitySofr Repo Funding Liquidity
ON RRP Facility Drainage & Rule 2a-7 Money Market Fund Rotation into Short T-BillsSofr Repo Funding Liquidity
NY Fed Standing Repo Facility (SRF) Usage: Auction Timing, Tri-Party Settlement & StigmaSofr Repo Funding Liquidity
DTCC FICC Sponsored DVP Repo: Multilateral Netting & ASC 210-20 Balance Sheet ReliefCorporate Credit Spread Cycles
iBoxx Total Return Swaps vs CDX Payer Swaptions: Cash-Spread Basis & Tail Convexity HedgingCorporate Credit Spread Cycles
Out-of-Court Distressed Debt Exchanges vs Prepackaged Chapter 11: The 38% Re-Default TrapCorporate Credit Spread Cycles
Reverse Yankee Corporate Bond Issuance: EUR/USD Cross-Currency Basis & ECB-Fed ArbitrageInflation Breakevens Real Rates
5y5y Forward Inflation Swaps vs TIPS Breakevens: Stripping Out Oil & Liquidity Noise
AlphaPulse Finance Data, Benchmarks & Contributor Records
CC BY 4.0 Open Data
Open Institutional Datasets (CSV / JSON) →
Download desk-compiled quantitative series & schemas.
2026 Reference Matrix
2026 Institutional Benchmarks & Thresholds →
Statutory capital, clearing, margin & rate conventions.
Editorial Records
Authors & Review Records →
View named contributors where those records are available.
Complete Index
Master Research & Dossier Archive →
Browse all published briefings by topic pillar & date.