
Quarter-End G-SIB Score Window Dressing & Foreign Bank Repo Pullbacks at Turn Dates
Asymmetric regulatory snapshot rules between US daily-average G-SIBs and foreign quarter-end bank dealers drive 15 to 45 bps repo turn spikes on March 31, June 30, September 30, and December 31.
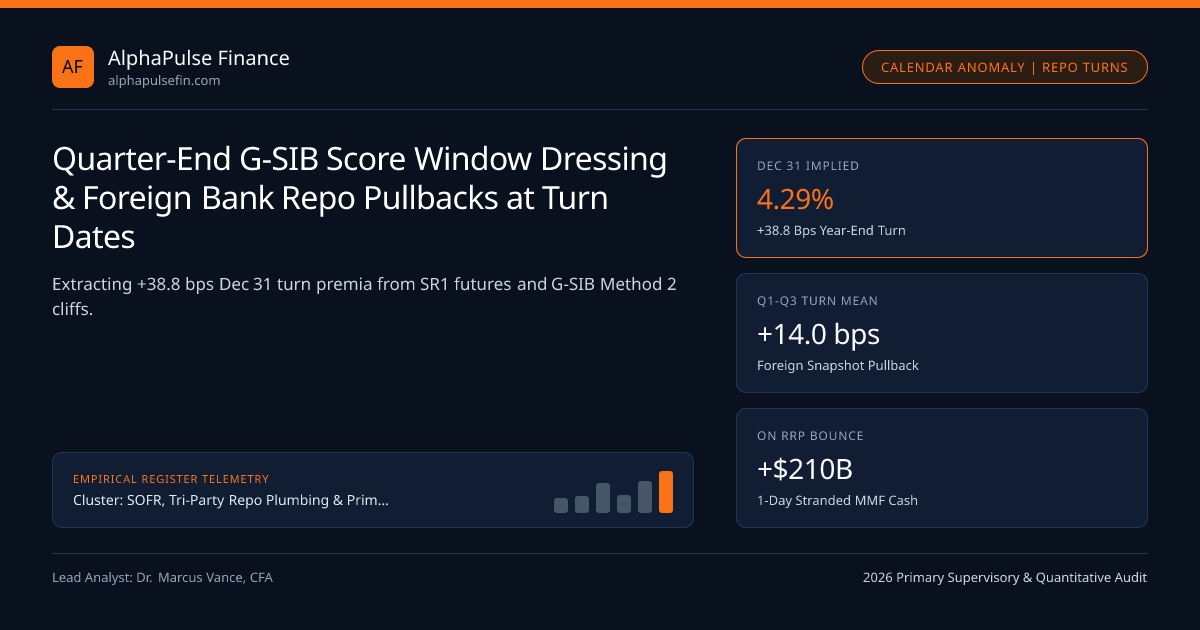
Like clockwork on the final business day of March, June, September, and especially December 31, the DTCC GCF Treasury Repo Index and bilateral DVP tails jump 15 to 45 bps above IORB while ON RRP balances briefly swell by +$200 billion—only to collapse back to 3.91% SOFR by 9:00 AM on the second business day of the new quarter. That recurring calendar anomaly is driven not by cash scarcity, but by Basel III regulatory accounting arbitrage across global systemically important bank (G-SIB) broker-dealers.
Daily-Average US Reporting vs Point-in-Time Foreign Bank Snapshots#
Why do European, Japanese, and Canadian primary dealer subsidiaries slash USD repo books by 25%-40% on the last day of each quarter while US G-SIBs hold relatively steady? Regulatory reporting frequency creates sharp jurisdictional asymmetry:
- US G-SIBs (FR Y-9C / FR Y-15): Supervised by the Federal Reserve and OCC, US bank holding companies calculate their Supplementary Leverage Ratio using quarterly averages of daily on-balance-sheet assets. Shrinking repo for one day on June 30 reduces a 91-day average by just 1/91st (~1.1%)—rendering single-day window dressing largely pointless except for year-end FR Y-15 Method 2 G-SIB Surcharge wholesale short-term funding buckets measured on December 31!
- Eurozone, UK, Swiss & Select Foreign Dealers: Several non-US jurisdictions historically assessed leverage disclosures, national bank levies, and resolution fund contributions using quarter-end or year-end point-in-time balance sheet snapshots (including Canadian dealers supervised by OSFI Canada managing quarter-end fiscal reporting).
Simultaneous Supply Collision: Month-End Coupon Settlement Meets Turn Pullback#
Quarter-end repo stress intensifies further because the US Treasury settles monthly 2-year, 5-year, and 7-year coupon auctions (~$183 billion gross par) on the exact last business day of the calendar month. Thus, at the precise 8:30 AM ET moment when foreign bank dealers withdraw $180B-$250B of matched-book lending capacity—sending rejected MMF cash straight into the 3.75% ON RRP window—primary dealers like Cantor Fitzgerald and leveraged basis funds must finance tens of billions of newly settled Treasury notes.
Forward-looking STIR traders price turn premia weeks in advance in 1-month CME SOFR futures (SR1) and forward-starting 1-day FICC Sponsored Repo ("the year-end turn"), often quoting December 31 -> January 2 overnight repo at +35 to +65 bps over surrounding days.
- ImpliedTurnRate = ((SR1MonthlyRate * TotalDays) - (DaysNormal * RNormal)) / DaysTurn
- Worked December CME 1-Month SOFR Future (SR1) Year-End Turn Extraction:
- December Total Days = 31 | Dec 31 -> Jan 2 Turn Weight (incl Jan 1 holiday) = 2 calendar days (29 normal days)
- Surrounding Normal SOFR = 3.900% | December SR1 Futures Price = 96.075 -> Implied Monthly Mean = 3.925%
- Implied Dec 31 Turn Rate = ((3.925% * 31) - (3.900% * 29)) / 2 = (121.675 - 113.100) / 2 = 4.2875% (+38.8 bps spike!)
Implied 1-Day Turn Rate Extraction from 1-Month SOFR Futures (SR1)#
Because 1-Month CME SOFR futures settle to the arithmetic average of daily SOFR across the calendar month, STIR desks isolate the exact market-implied year-end or quarter-end 1-day turn spike algebraically.
Jurisdictional Dealer Snapshot Rules & Turn Behavior Matrix#
Tracking which dealer cohorts step back versus step in on turn dates lets buy-side treasurers lock in term repo across quarter-ends 3 to 4 weeks early.
| Dealer Regulatory Cohort | Leverage Reporting Basis | Q1-Q3 Turn Pullback | Dec 31 Year-End Pullback | Supervisory Authority |
|---|---|---|---|---|
| US G-SIB Bank Dealers | Daily Quarterly Average | Low (-4% to -8%) | High (-18% FR Y-15 Cliff) | Federal Reserve / OCC |
| Eurozone & UK Bank Dealers | Mix Avg / Snapshot Levies | High (-28% to -38%) | Severe (-42% Bank Levy) | ECB / PRA + SEC US Sub |
| Canadian Bank Dealers | Fiscal Qtr (Jan/Apr/Jul/Oct) | Shifted Calendar | Moderate (Oct 31 Year-End) | OSFI Canada / IIROC |
| Independent Non-Bank Dealers | SEC Rule 15c3-1 Net Cap | Expands (+15% to +22%) | Expands (+25% Spread Harvest) | SEC / FINRA (Cantor) |
December 31 G-SIB Method 2 Surcharge Cliff Risk for US Megabanks#
While US G-SIBs average SLR daily, the Federal Reserve's Method 2 G-SIB Capital Surcharge (which sets CET1 capital buffers in 50-bps steps from 1.0% to 4.5%+) still incorporates year-end December 31 indicators for cross-jurisdictional claims, intra-financial liabilities, and Complexity/Wholesale Funding scores. Any US megabank sitting within 15 points of a +50 bps CET1 bucket boundary aggressively sheds unnetted bilateral reverse repo between December 15 and December 31, making year-end turns 2.2x larger than Q1-Q3 turns.
Macro allocation frameworks connect this note to SOFR, Tri-Party Repo Plumbing & Primary Dealer Balance Sheets, Basel III Supplementary Leverage Ratio (SLR, and Corporate Tax Deadlines, TGA Inflows &, indexed under SOFR alongside verification registry.
Frequently asked questions
How can SOFR spike above 4.15% on quarter-end at the exact same time $200B flows into 3.75% ON RRP?
Money market funds have cash to lend, and hedge funds want to borrow it, but bank dealers refuse to expand balance sheets on the snapshot date to connect them—forcing MMFs into 3.75% ON RRP while borrowers bid up scarce remaining dealer space.
Why do Canadian primary dealers pull back in late January, April, July, and October instead of March/June/Sept/Dec?
Major Canadian Schedule I banks supervised by OSFI operate on fiscal quarters ending January 31, April 30, July 31, and October 31, shifting their balance sheet discipline off the standard US/European calendar.
How do leveraged basis funds protect themselves against December 31 repo turn spikes?
Basis desks lock in 1-month or 6-week term FICC Sponsored Repo in late November ("terming over the turn"), paying a steady +4 to +6 bps annualized premium to guarantee uninterrupted funding past January 2.
Why did the Federal Reserve propose averaging FR Y-15 G-SIB systemic indicators across the full year?
Switching FR Y-15 systemic risk indicators from December 31 snapshots to daily/quarterly averages removes the artificial incentive for US G-SIBs to shrink repo intermediation exclusively during the final two weeks of December.
Publication record
- Published
- November 14, 2026
- Updated
- November 14, 2026
- Author
- Dr. Marcus Vance, CFA
- Review
- Review not recorded
- Automated fact check
- Passed in the stored pipeline record
- Source URLs
- 3 recorded
AI assistance recorded: anthropic/claude-opus-4.6. This field does not establish human review or source verification.
Academic & Institutional Attribution
Cite This Research & Embed Live Data Card
Standard academic & institutional research paper citation format.
Dr. Marcus Vance, CFA. (2026, November 14). Quarter-End G-SIB Score Window Dressing & Foreign Bank Repo Pullbacks at Turn Dates. AlphaPulse Finance. https://alphapulsefin.com/analysis/quarter-end-gsib-surcharge-window-dressing-repo-rate-spikesRelated Sofr Repo Funding Liquidity & Institutional Briefings
Explore Sofr Repo Funding Liquidity Hub (20) →Sofr Repo Funding Liquidity
SOFR, Tri-Party Repo Plumbing & Primary Dealer Balance Sheets: Money Market GuideSofr Repo Funding Liquidity
Basel III Supplementary Leverage Ratio (SLR & eSLR) Constraints on Treasury Repo DealersSofr Repo Funding Liquidity
BNY Tri-Party vs FICC GCF & Bilateral DVP Repo: Funding Rate Segmentation & SpreadsSofr Repo Funding Liquidity
Federal Home Loan Bank (FHLB) Liquidity Arbitrage: Fed Funds Lending vs Discount WindowSofr Repo Funding Liquidity
On-the-Run Treasury Specials in Repo, Fails-to-Deliver & TMPG 300-Bps Penalty MechanicsSofr Repo Funding Liquidity
OFR Non-Centrally Cleared Bilateral Repo (NCCBR) Data: Zero-Haircut Hedge Fund LeverageSofr Repo Funding Liquidity
CME 3-Month vs 1-Month SOFR Futures: Rate-Volatility Convexity Bias vs Forward OISSofr Repo Funding Liquidity
Corporate Tax Deadlines, TGA Inflows & SOFR 99th-Percentile Intraday Funding SpikesCorporate Credit Spread Cycles
Fixed-Income Credit ETF Create/Redeem Arbitrage: Custom Baskets & Stale-NAV Liquidity DiscoveryCorporate Credit Spread Cycles
US BSL CLO Arbitrage: AAA Liability Spreads, 7.5% CCC Buckets & Junior OC Test DiversionCorporate Credit Spread Cycles
Private Credit Unitranche PIK Toggles & BDC Non-Accrual Dispersion: Shadow Default AuditCorporate Credit Spread Cycles
Merton Structural Distance-to-Default: Equity Put Skew Leading Corporate Credit Spreads
AlphaPulse Finance Data, Benchmarks & Contributor Records
CC BY 4.0 Open Data
Open Institutional Datasets (CSV / JSON) →
Download desk-compiled quantitative series & schemas.
2026 Reference Matrix
2026 Institutional Benchmarks & Thresholds →
Statutory capital, clearing, margin & rate conventions.
Editorial Records
Authors & Review Records →
View named contributors where those records are available.
Complete Index
Master Research & Dossier Archive →
Browse all published briefings by topic pillar & date.